

Building the Fintech Dream


The Latest Content
What if your fraud prevention controls are working exactly as designed, and that is precisely the problem?
Across the United States, risk and compliance teams are closing cases, clearing alerts, and reporting fraud losses within acceptable thresholds, while a completely different category of financial crime is scaling invisibly underneath those metrics.
Most AI fraud prevention strategies in use today were built around human fraudsters making human mistakes and leaving human traces. But the dominant fraud threat of 2026 is not human. It is algorithmically generated, behaviorally convincing, and specifically engineered to look clean inside the very systems designed to catch it. Synthetic identity fraud alone is projected to cost US businesses between $30 and $35 billion annually, and it now accounts for up to 80% of all new account fraud, yet represents only 4% of fraud cases by frequency. That gap between frequency and financial impact is exactly what makes it so dangerous and so difficult to act on.
The uncomfortable reality is that AI has not just changed how fraud is committed. It has fundamentally changed what fraud looks like.
AI-Driven Fraud Is Rewriting Financial Crime in the US
For most of the past decade, fraud in the United States followed a recognisable pattern. A stolen credential, a compromised account, a suspicious transaction that triggered an alert. The tools built to catch it were designed around that pattern, and for a long time they worked reasonably well. That era is over.
Fraudsters in 2026 are operating AI systems that run continuously, adapt in real time, and are specifically engineered to exploit the gaps in conventional fraud detection and prevention infrastructure. These are not isolated criminal actors making opportunistic moves. They are organised networks deploying machine learning to manufacture false identities, generate convincing synthetic documents, and automate attacks at a scale that human review cycles simply cannot match.
What this shift looks like in numbers:
- US businesses reported losing 9.8% of annual revenue to fraud in 2025
- AI-enabled fraud losses are projected to reach US$40 billion in US by 2027
These are not numbers that reflect a problem under control. They reflect a problem that has been consistently underestimated because the most damaging fraud category barely registers in case frequency data while quietly driving an outsized share of total financial losses.
Synthetic Identity and Deepfakes: One Industrialised Threat
Generative AI has given fraudsters something they never previously had, which is the ability to manufacture a believable human identity at scale and use it to systematically extract money from financial systems over an extended period of time.
A synthetic identity fraud profile combines real data fragments, typically a legitimate Social Security number paired with a fabricated name, address and contact details, to create a person who does not exist but passes every standard verification check. This identity is then used to open financial accounts, build a credit history through months of normal-looking activity, and steadily increase available credit limits until the fraudster decides the ceiling is high enough. At that point every credit line is maxed simultaneously, the funds are moved and the identity is discarded, leaving no real victim to file a report and no trail meaningful enough to follow.
The one control that historically stood between a synthetic identity and a fully operational account was biometric verification. Deepfake technology has made that control increasingly unreliable:
- Fraud attempts leveraging deepfake content have climbed more than 2,137% over the last three years
- Around 1 in every 5 biometric fraud attempts now involves face swaps or animated selfie manipulation engineered specifically to defeat liveness detection
- Only 13% of companies currently run any anti-deepfake protocols, meaning the vast majority of US businesses are encountering this threat without a specific defense against it
These are not two separate problems requiring two separate responses. They are sequential steps in the same industrialised pipeline, and together they have made AI-driven fraud detection one of the most urgent and least solved challenges in US financial services today.
Detect deepfakes. Block synthetic identities.
Synthetic identities are not just used to access credit. They are used to build the infrastructure through which fraudulent funds move internationally:
- Money mule networks exploit remittance corridors specifically because monitoring across jurisdictions is fragmented
- Each leg of a cross-border transaction obscures the origin of funds further, making the trail progressively harder to follow
- By the time a suspicious pattern surfaces, the money has typically already cleared several intermediary accounts across multiple geographies
The regulatory environment adds further pressure on US businesses managing cross-border flows:
- FinCEN requirements, OFAC sanctions obligations and state-level MSB regulations each carry distinct monitoring and reporting demands
- Businesses handling high transaction volumes across multiple corridors carry significant exposure when these are treated as separate obligations rather than a connected compliance framework
- Fraud monitoring and regulatory compliance handled in silos means organised fraud networks find the gaps before you do
Effective cross-border remittance fraud prevention was never about more tools. It was always about a single connected view.
Why Traditional Fraud Prevention Software Is Failing
The fundamental problem with most fraud prevention software currently in use across the US is not that it is poorly built. It is that it was built for a different threat environment entirely.
The Fraud Detection Gap:
When fraud is specifically designed to look normal, a system built to detect abnormality will consistently miss it. Rule-based transaction monitoring flags anomalies based on predefined patterns. Synthetic identities do not produce anomalies. They produce clean transaction histories, healthy credit scores and behaviours that look entirely legitimate until the moment they do not.
Traditional adverse media screening faces the same structural problem. Keyword-based systems flag anyone mentioned near a negative term regardless of their actual role in the story. A judge presiding over a fraud trial triggers the same alert as the defendant. Hundred articles covering the same incident generate hundred separate alerts. The result is alert fatigue that is not just an operational inconvenience but a genuine compliance risk, because when analysts are buried in noise, the signals that actually matter get missed. AI-driven fraud detection systems have demonstrated the ability to reduce false positives by 65 to 90%, which gives a reasonable indication of how much noise currently exists inside conventional systems.
What Effective AI Fraud Prevention Looks Like in Practice?
Genuine AI fraud prevention in 2026 is not about replacing one set of rules with a smarter set of rules. It is about understanding context, behaviour and risk continuously, across the entire customer lifecycle.
Behavioral intelligence over transaction rules
- Builds a continuous model of how each customer normally operates
- Detects deviations from individual behavioral baselines, not just known fraud patterns
- Catches synthetic identity bust-outs before execution because the behavioral shift preceding them is visible even when the transaction looks routine
Context-aware AI adverse media screening
- Distinguishes between a perpetrator, witness, judicial authority and victim mentioned in the same article
- Clusters related coverage of the same event into a single alert rather than one notification per publication
- Tracks event progression from investigation through to conviction, updating risk profiles dynamically
Perpetual KYC
- Replaces point-in-time onboarding snapshots with continuously updated customer risk profiles
- Triggers reviews when risk signals change rather than waiting for scheduled periodic reviews months away
Real-time fraud monitoring
- Real-time systems prevent substantially higher fraudulent transactions than batch-based processing
- When synthetic identities execute bust-outs across hundreds of accounts simultaneously, the difference between real-time and near-real-time detection is measured in millions of dollars
The businesses best positioned to handle AI-driven fraud are not those with the most tools. They are those with the most integrated tools, where identity verification, screening, behavioral analytics, transaction monitoring, threshold monitoring and regulatory reporting function as a single connected system rather than separate functions with blind spots between them.
Your 2026 Fraud Prevention Checklist
Before your next compliance or risk review, work through these:
- Are your fraud controls built around behavioral signals or purely transaction rules?
- Can your adverse media screening distinguish between a perpetrator and a witness in the same news article?
- Does your cross-border payment monitoring operate as a unified layer or as separate domestic and international functions?
- Are your customer risk profiles updated continuously or only at scheduled review intervals?
- Have you assessed your exposure to deepfake-enabled verification bypass attempts?
- Does your fraud monitoring cover behavioral and device intelligence beyond transaction data alone?
- Can your system detect synthetic identity patterns before a bust-out rather than after?
The Cost of Standing Still Is No Longer Acceptable
The fraud environment facing US businesses in 2026 demands a response that matches the sophistication of the threat. The businesses that navigate this successfully will be those that treat fraud detection and prevention as a unified, AI-powered function rather than a collection of point solutions that communicate only when something has already gone wrong.
FlexM, a leading global fintech conglomerate trusted by over 400+ businesses across the world, has spent over a decade building exactly this kind of integrated infrastructure, purpose-built for the complexity that modern financial crime demands.
The conversations happening this week at New York Fintech Week 2026 in Manhattan, among founders, risk leaders and compliance heads, reflect precisely the urgency that businesses across the US are waking up to. Fraud prevention in an AI-driven world is no longer a back-office compliance exercise. It is a strategic business priority, and the question every US business needs to answer is whether their defenses were built for the version of fraud that already exists today.
Identify gaps across behavior, identity, and real-time risk detection

When Nigeria exited the FATF grey list in October 2025, it was a defining moment for the country's financial system. Years of regulatory reform, institutional coordination and political will had finally paid off. But that exit was never meant to be a finish line. It was a starting point.
The CBN's March 2026 circular has made that unmistakably clear. Every regulated financial institution in Nigeria, from deposit money banks to mobile money operators to payment service providers, must now deploy automated AML solutions that meet new CBN AML requirements 2026. And the first critical deadline is already around the corner: implementation roadmaps must be submitted to the CBN's Compliance Department by June 10, 2026.
For compliance leaders who have spent years navigating manual processes, fragmented systems and growing regulatory expectations, this circular changes the game. It is the most consequential financial crime compliance directive Nigeria has seen in years, and it demands a level of technological readiness that most institutions have not yet achieved.
What Has the CBN Mandated and Who Does It Apply To?
The CBN's March 2026 circular (referenced as BSD/DIR/PUB/LAB/019/002), establishes mandatory CBN baseline standards for AML across the entire regulated financial sector. These standards apply to all financial institutions currently operating under CBN regulation; furthermore, applicants for new licenses must also demonstrate compliance or present a credible implementation plan as part of the authorization process.
The circular introduces three compliance milestones that every institution needs to plan around:
The implementation roadmap is more than a plan; it is a formal regulatory submission that demands absolute precision. To satisfy this requirement, the document must include:
- A current-state assessment and gap analysis to pinpoint specific vulnerabilities.
- The proposed AML solution architecture.
- A phased timeline featuring named milestones and clear owners for every workstream.
- A robust governance and oversight framework.
- A committed resource and budget plan.
This submission requires the highest level of internal accountability, finalized with the signatures of both the CEO and the Chief Compliance Officer.
The CBN is clear that compliance is not a checkbox exercise. The regulator will evaluate demonstrable effectiveness rather than vendor-driven implementation. In practice, simply having a system in place is no longer the benchmark. The regulator now requires proof that the solution delivers measurable results in:
- Detecting complex financial crime patterns.
- Facilitating thorough investigations.
- Maintaining precise, timely reporting.
The 12 Baseline Capabilities That Will Define CBN Compliance 2026
The circular sets out 12 capability areas that every automated AML solution must support. For institutions still relying on manual processes or disconnected point solutions, this list serves as the definitive benchmark against which the CBN will measure readiness.
One requirement in the circular is worth highlighting separately. The CBN has explicitly stated that AML solutions operating solely on transaction data, without effective linkage to customer identity, risk profiles and case histories, will not be considered compliant. Institutions rated High or Above Average risk within their subsector are specifically required to ensure full integration between their AML systems and their KYC/KYB repositories. This effectively ends the era of siloed compliance architecture in Nigeria's financial sector.
Get Your Free Guide
A complete, easy-to-use guide for your gap analysis
Why Is This Circular Different from Previous Nigeria AML Regulations?
Nigerian financial institutions have seen plenty of regulatory updates over the years. So what makes this one stand out?
- Accountability now sits at the top
Compliance is no longer just an institutional responsibility. The circular makes it clear that board members, CEOs, and Chief Compliance Officers can be held personally accountable. A compliance failure is now a direct leadership risk.
- Explainable AI is a regulatory requirement
The CBN has formally introduced AI and machine learning governance into its AML framework. Institutions must deploy automated AML systems, with expectations scaled to their size and risk profile.- Larger institutions are expected to use advanced AI-driven systems
- Smaller institutions can adopt proportionate solutions, but must still meet baseline requirements
- Strict AI governance expectations apply
Any use of AI or ML must include:- Human oversight
- Algorithm transparency and explainability
- Clear reasoning behind every alert generated
- Independent validation at least annually, covering accuracy, drift, fairness, and bias
- FATF Compliance depends on execution
Nigeria’s exit from the FATF grey list was a major milestone. This circular is about sustaining that progress. The CBN is signalling that compliance must be continuous, measurable, and evolving to maintain global credibility.
What Is Actually Holding Institutions Back?
The directive is clear and well-structured. But across the sector, readiness remains a significant concern. What are compliance teams actually up against?
The fraud numbers reinforce the urgency. Nigerian banks lost ₦3.3 billion to fraud in the first quarter of 2025 alone, a 137% increase from ₦1.39 billion in the previous quarter. For institutions still managing financial crime compliance Nigeria requirements through manual and fragmented setups, the risk of falling behind is not theoretical.
Disconnected systems are still common. Identity verification and AML processes often run on separate platforms with limited data sharing. The CBN requires integration across AML systems, core banking, and KYC or KYB data to enable a unified customer view.
The CBN also encourages a unified financial crime setup where AML and fraud systems share risk signals. This means many institutions must rethink how their systems connect and operate.
Too many tools, not enough integration. Nigeria’s RegTech market has expanded, but many solutions are single-purpose. Institutions need to assess vendors based on API capabilities, integration depth, and their ability to support end-to-end compliance needs.
A Step-by-Step CBN Compliance Roadmap to Get Ready Before June 2026
With the June 10 deadline approaching, institutions need a structured approach that meets CBN expectations and supports long-term compliance.
Start with a clear gap analysis. Map your current capabilities against the 12 baseline areas in the circular. Identify what is compliant, where gaps exist, and where systems are misaligned. This forms the foundation for all next steps.
Evaluate system integration. Does your AML case management system connect to your KYC records and customer risk profiles? Does your transaction monitoring engine assess activity within the context of the full customer profile, or does it operate on raw transaction data alone? The CBN has stated clearly that the latter approach is not acceptable.
Prioritise near real-time screening and monitoring. This includes sanctions screening, PEP checks with fuzzy matching, suspicious activity detection across channels, and the ability to block onboarding or transactions instantly when needed. Batch processing is no longer sufficient.
Prepare a Board-authorised implementation roadmap. This must be submitted to the CBN Compliance Department by June 10. Include your gap analysis, solution architecture, phased timeline, governance framework, and sign-off from the CEO and Chief Compliance Officer.
Embed AI governance early. If using AI or ML for risk scoring or detection, document validation processes, explainability standards, and bias testing. The CBN expects outputs that investigators can clearly interpret.
Focus on continuous compliance. The CBN will monitor through ongoing reviews and examinations. Institutions that build for transparency, governance, and continuous improvement will be better positioned than those treating this as a one-time task.
Building Compliance Infrastructure That Outlasts the Deadline
The institutions that will emerge strongest from this transition are those that see the CBN's March 2026 circular not as a regulatory burden but as a catalyst to build compliance infrastructure that delivers lasting value.
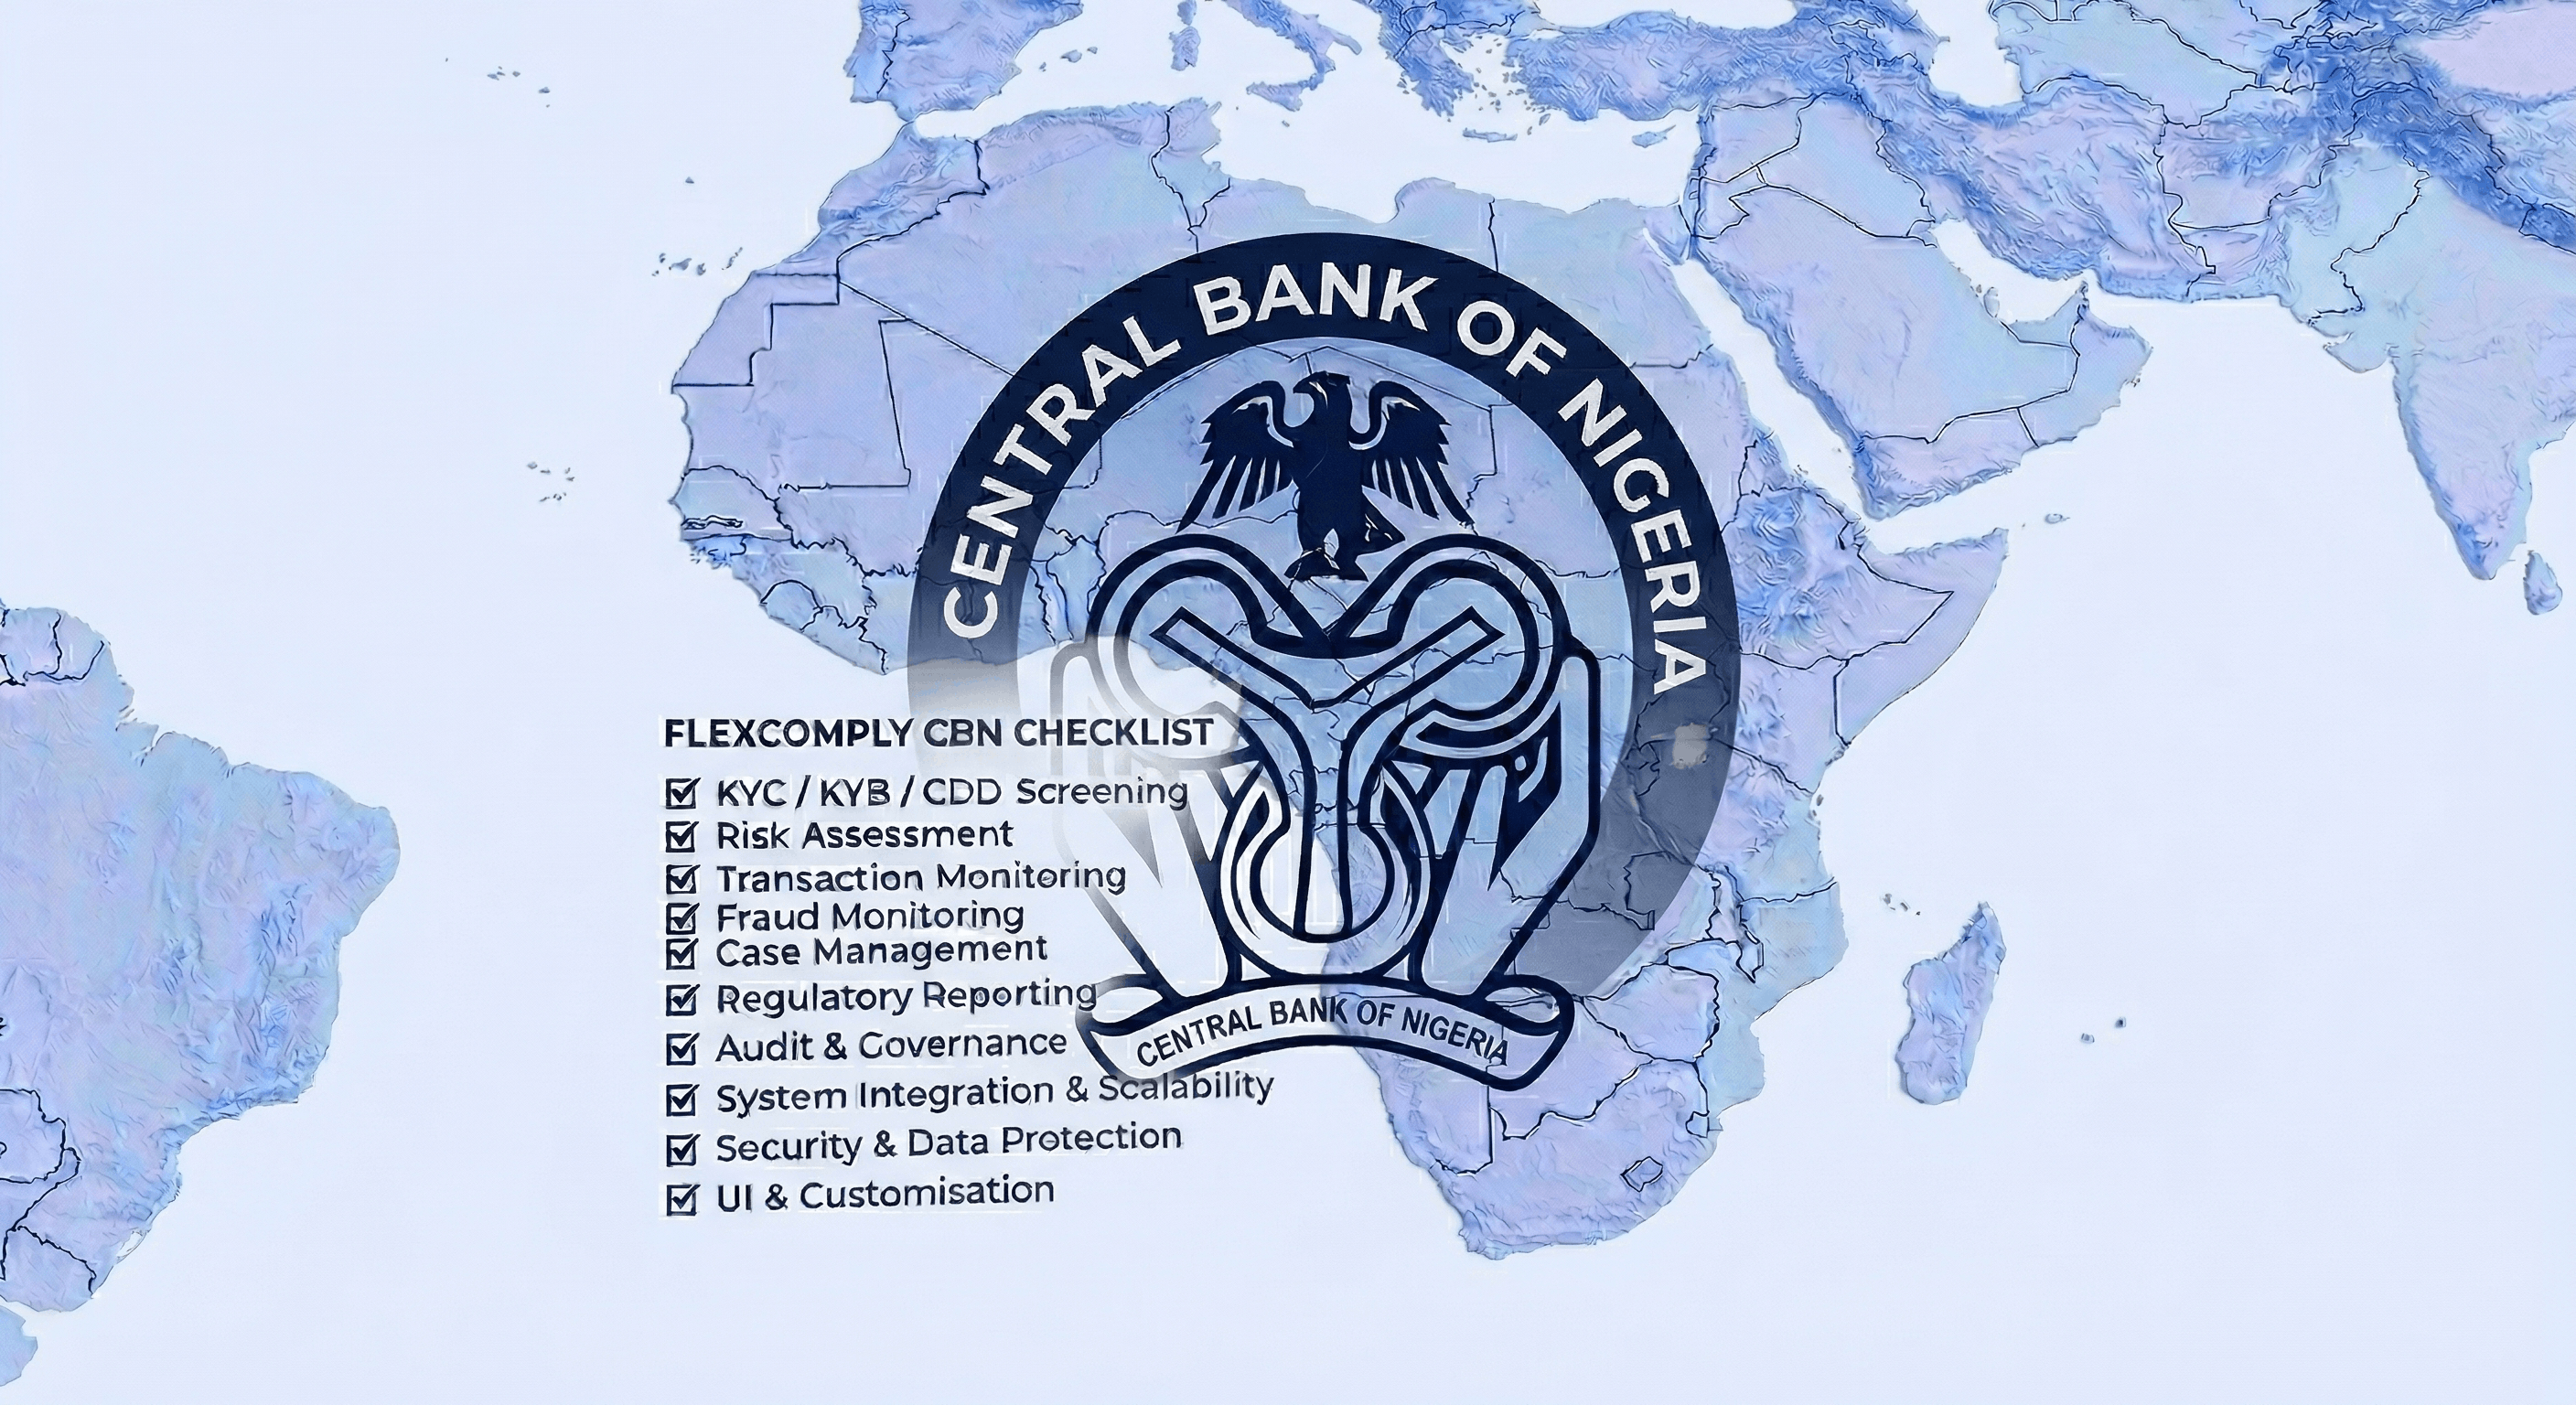
FlexM, the leading global fintech conglomerate, offers FlexComply, a 360-degree compliance technology platform designed for exactly this and beyond. As a unified FRAML platform, FlexComply addresses all 12 CBN AML requirements 2026 within a single integrated infrastructure.
Furthermore, FlexComply's AI-powered adverse media screening goes beyond keyword-based matching, using context-aware entity recognition and role-based adversity logic to deliver high-precision alerts with significantly fewer false positives. In a regulatory environment where the CBN now expects explainable AI outputs and continuous monitoring as part of its baseline standards, this capability is no longer optional.
CBN compliance 2026 is not about meeting a single deadline. It is about building the kind of financial crime compliance architecture that earns confidence from regulators, international partners and customers for years to come.
Ready to see where your institution stands against the CBN's 12 baseline requirements?
Get a tailored compliance gap analysis. No sales pitch, just expertise
Money Service Businesses sit at the center of an increasingly complex financial ecosystem. They move value across borders, connect legacy finance with emerging fintech models, and serve millions of customers who rely on fast, compliant and reliable services. But as the sector expands, so do its operational and regulatory vulnerabilities. Even well-established MSBs are finding that growth exposes gaps their legacy systems cannot absorb — a pattern consistently highlighted by leading global fintech conglomerates like FlexM, whose modular platform architecture is built specifically for MSB scalability. In this environment, choosing a scalable Money Service Business platform has become a structural, not optional, decision.
The Industry Has Outgrown Its Traditional Infrastructure
Money Service Businesses now operate within one of the fastest-expanding and most complex financial environments in the world. The scale of value moving across borders has fundamentally shifted. The global cross-border payments landscape is projected to reach US $290 trillion by 2030, signalling not only rapid expansion but also an urgent need for more resilient, intelligent infrastructures capable of supporting such unprecedented flows.
At the same time, the global remittance market — a core operational channel for MSBs — is expected to reach US $744.8 billion in 2025. This surge highlights just how central MSBs have become to cross-border value movement, financial inclusion, and alternative financial rails.
Yet despite this scale, MSBs often operate on outdated, fragmented systems built for a different era. Manual onboarding, spreadsheet-driven reconciliations, disconnected AML tools, and channel-specific workflows all create bottlenecks that compound as the business grows. A modern money service business software resolves these limitations by creating a unified ecosystem where customer onboarding, risk scoring, monitoring, and reporting operate cohesively rather than in silos.
Regulation Has Entered a New Phase — and Money Service Business Platform Are on the Front Line
Compliance is no longer episodic; it is continuous.
The most significant example of this shift came in October 2025, when Canada introduced sweeping AML reforms that tighten MSB registration, strengthen sanctions-reporting requirements, and elevate expectations for transaction traceability and governance oversight. These changes signal an international trend: regulators expect MSBs to demonstrate control, transparency, and auditability at the same level as major financial institutions.
This rise in scrutiny makes a scalable MSB compliance platform indispensable. Instead of retrofitting new rules into legacy processes, MSBs require systems that adapt in real time — recalibrating workflows, updating risk logic, recording audit trails, and supporting ongoing monitoring automatically. FlexM’s modular compliance stack, for example, enables MSBs to adjust rapidly to regulatory shifts without operational disruption.
How a Unified MSB management system Reduces Operational Risk
While regulatory pressure is highly visible, operational strain often becomes the hidden obstacle that prevents MSBs from scaling. As MSBs add new corridors, payout partners, digital channels, agent networks, and customer types, their internal complexity grows exponentially.
This increased complexity typically manifests as:
- inconsistent onboarding decisions
- duplicated customer records across systems
- slow case resolution due to manual reviews
- siloed data resulting in incomplete risk views
- rising operational cost as teams expand linearly with volume
A scalable MSB management system alleviates these issues by consolidating data, automating repetitive workflows, standardizing decision logic, and giving compliance and operations teams a unified real-time view of customer and transaction activity. This reduces cost-to-serve, lowers error rates, and allows MSBs to expand sustainably.
Customer Experience Has Become the Real Test of Modern money service business software
Modern MSB customers expect:
- fast, seamless onboarding
- real-time transaction visibility
- consistent decisioning
- predictable turnaround times
- omnichannel continuity
Whether these customers are individuals, SMEs, marketplaces, or digital platforms, they expect immediacy and clarity — expectations that strain fragmented systems.
A unified money service business software ensures that customer journeys remain consistent even under heavy transaction loads. FlexM’s customer-centric architecture demonstrates how MSBs can maintain service standards while supporting complex multi-corridor, multi-partner environments.
Why Scalability Defines the Next Generation of MSB Leaders
For MSBs, scalability means far more than handling additional volume. It means:
- Regulatory scalability: adapts to new rules, jurisdictions, and reporting structures without painful system rebuilds.
- Operational scalability: workflows remain stable and efficient as activity multiplies.
- Risk scalability: monitoring improves with scale, rather than degrading under pressure.
- Customer scalability: experience quality remains consistent across channels and growth cycles.
- Technology scalability: infrastructure remains reliable during peak loads and expansion phases.
This is the type of scalability required to survive the next decade of regulatory and competitive transformation.
Scalable Money Service Business Platform: The New Competitive Edge
The MSB industry is entering its defining period. Transaction volumes are rising, compliance expectations are intensifying, and customer journeys are becoming more digital and demanding. A scalable Money Service Business platform is no longer an optional upgrade. It is the backbone of MSBs that intend not only to grow, but to lead in a sector where resilience, adaptability, and compliance readiness define long-term success.
FlexM’s modular ecosystem — both compliance, and remittance — gives MSBs a single, integrated foundation built for real-world scale. Discover how your MSB can modernize with confidence: visit flexm.com to learn more.
In today’s hyper-regulated financial landscape, compliance is not just a checkbox—it’s the backbone of operational trust and long-term scalability. For fintechs, money service businesses (MSBs), and emerging digital banks, the ability to manage compliance seamlessly is critical to sustainable growth.
Financial institutions spend billions annually on compliance. The overall market for financial crime compliance is projected to reach over $55.47 billion by 2032, indicating a massive increase in spending and a growing reliance on technology to manage these costs. This makes selecting the best compliance management software for fintech not only a strategic choice but also a competitive differentiator. FlexM, a leading global fintech conglomerate, with its award-winning compliance platform, FlexComply, has been at the forefront of empowering regulated entities to simplify compliance while scaling with confidence.

The Rising Importance of Compliance in Fintech
Early enforcement actions in 2025 show regulators intensifying their focus on fintechs, neobanks, and digital financial platforms. In the U.S., LPL Financial received a $3 million FINRA penalty for AML failures tied to penny stock surveillance, while Block Inc. (Cash App) faced a coordinated $80 million multi-state enforcement action for BSA/AML program deficiencies. These early cases signal a proactive regulatory stance toward emerging financial platforms and newer risk vectors across the digital finance ecosystem.
As fintechs expand across borders, compliance demands become more complex—spanning AML/CFT obligations, data protection laws, and dynamic KYC/KYB requirements. The challenge is no longer just about adhering to regulations; it’s about doing so efficiently, without stifling innovation. That’s where compliance management solutions steps in—integrating automation, AI, and analytics to transform risk oversight into a proactive advantage.
Fintech startup platforms Singapore and across Asia, for instance, face some of the world’s most rigorous compliance standards under the Monetary Authority of Singapore (MAS). For such players, adopting a scalable fintech platform for MSBs ensures alignment with multiple jurisdictions while minimizing manual oversight. The goal is to stay audit-ready, reduce false positives, and improve decision-making—all through a unified compliance lens.
Key Features to Look For
- Comprehensive Identity Verification
A good compliance solution must support real-time KYC/KYB verification, This not only enhances user trust but accelerates onboarding without compromising regulatory requirements.
- Automated Screening & Monitoring
Continuous screening against global sanctions, PEPs, and adverse media lists is vital. The best compliance management software for fintech automates these checks, offering ongoing monitoring that updates dynamically as new data emerges.
- Risk-Based Assessment Frameworks
Fintechs need adaptive risk scoring—factoring customer behavior, geography, and transaction velocity. Scalable platforms can customize these rules to fit business models while staying regulatorily compliant.
- Transaction and Threshold Monitoring
Smart monitoring tools detect unusual activities in real time, flagging suspicious transactions before they escalate. Automation helps teams prioritize alerts based on severity rather than volume.
- Regulatory Reporting & Case Management
Automated STR/SAR generation, complete audit trails, and unified case management dashboards make investigations faster and more transparent—
- Automation-Driven Analytics
Machine learning can predict emerging compliance risks by analyzing patterns across customer segments and jurisdictions.
How Scalability Shapes Compliance Success
Startups often choose tools that solve immediate problems, but as they expand, they realize the need for scalable, modular solutions. A modular banking infrastructure fintech approach enables seamless integration of new regulatory features, APIs, and data models without overhauling existing systems. This agility ensures fintechs can stay compliant as they grow—launching new products, entering new markets, or integrating with new payment networks.
FlexComply, for example, has built its compliance framework to scale effortlessly with clients’ business growth. Its modular architecture lets financial institutions integrate compliance modules—such as AML, transaction monitoring, or UBO discovery—individually or as a full suite. This flexibility allows MSBs and digital banks to tailor solutions to their specific operational needs.
The Future of Compliance Solutions in Fintech
The next generation of compliance management will focus on predictive intelligence—systems that flag potential breaches before they happen. Cloud-native solutions, AI dashboards, and perpetual KYC frameworks will redefine compliance from reactive to anticipatory. Moreover, as digital identity standards evolve globally, interoperability between fintech ecosystems will become a compliance mandate in itself.
FlexComply continues to embody this vision—merging compliance, scalability, and innovation into a single, unified ecosystem. For fintech startup platforms Singapore and beyond, this marks the evolution from manual monitoring to intelligent, data-driven governance.
Final Thoughts
As fintechs expand across borders and digital financial ecosystems grow more complex, compliance can no longer function as a reactive function—it must operate as a strategic engine for trust, growth, and operational resilience. Choosing the best compliance management software for fintech is ultimately about enabling scale without sacrificing regulatory integrity. For MSBs navigating high-volume, multi-corridor environments, only a scalable fintech platform for MSBs can support the pace, risk, and oversight required in today’s landscape. And as product lines, partners, and jurisdictions evolve, adopting a modular banking infrastructure fintech approach ensures compliance capabilities can adapt in lockstep with business change. Companies like FlexM demonstrate how long-term compliance strength is built not through scattered tools, but through unified, scalable infrastructure that empowers fintechs to grow confidently. To learn more visit flexcomply.flexm.com or flexm.com.
Global regulators are taking a firmer stance as financial crime grows more complex and harder to detect. Recent enforcement actions have shown how quickly compliance gaps can escalate into major reputational and financial damage. Whether it is FinCEN issuing a USD 3 billion penalty to a leading North American bank or FINTRAC issuing $600K fine to a Canadian bank for failing to submit suspicious transaction reports, the pattern is the same: regulators expect stronger controls, real-time oversight, and auditable intelligence across every customer and transaction touchpoint.
For banks and fintechs, choosing the best AML compliance software in 2026 has become essential to protecting customer trust and maintaining regulatory confidence. Compliance is no longer just an operational requirement. It is a strategic defence against penalties, reputational loss, and operational disruption. This is where platforms like FlexComply, the award-winning, 360-degree compliance solution from global fintech leader FlexM, deliver meaningful value by offering a modular and intelligent ecosystem that helps institutions not only stay compliant but dramatically reduce the reputational fallout and financial exposure associated with regulatory penalties.
The Evolving Landscape of AML Automation for Financial Institutions
Today’s financial ecosystems span cross-border payments, embedded finance, digital wallets and real-time settlement environments. With every transaction carrying potential risk, manual reviews and disconnected systems simply cannot keep pace. This is why AML automation for financial institutions has become a foundational requirement for modern compliance teams.
The global digital payments market is projected to reach USD 19.89 trillion by 2026, growing at a CAGR of 24.4%. As transaction volumes accelerate, regulators are demanding more rigorous controls: smarter analytics, continuous monitoring and fully auditable reporting.
Key Capabilities That Define the Best AML Compliance Software
Modern compliance technology must do more than detect suspicious activity. The best AML compliance software in 2026 will be defined by following foundational capabilities:
- Unified Risk Intelligence – Integrating KYC, sanctions screening, transaction monitoring and customer risk scoring into one dashboard reduces false positives and improves visibility.
- Real-Time Transaction Monitoring Automation AML – AI and behavioral analytics enable institutions to detect unusual activities across borders and currencies instantly.
- Modular Scalability – A flexible AML solution platform for banks & fintechs should allow rapid adaptation to new regulations or geographies through API-first integration.
- Audit-Ready Reporting and Transparency – Generating Suspicious Transaction Reports (STRs) and audit logs automatically ensures accuracy and accountability.
Platforms like FlexComply already embed these capabilities within a unified, modular ecosystem—bridging innovation and regulation to help institutions stay one step ahead of evolving financial crime risks.
From Manual Oversight to Intelligent Automation
Traditional compliance teams spend a major chunk of their time on manual alert reviews and data collection, which creates inefficiencies—not only in manpower hours but also in the ability to detect evolving risks effectively. As financial ecosystems grow more complex, these manual processes can no longer keep pace with the volume and velocity of transactions.
This is where automation becomes the cornerstone of digital transformation. Intelligent transaction monitoring automation AML systems use behavioral analytics to learn from patterns across geographies, currencies, and counterparties. Instead of static rule libraries, they dynamically adapt to new typologies. These innovations give compliance analysts back their time to focus on investigation, not noise. And for customers, it translates to smoother onboarding, fewer verification delays, and greater trust that their data is handled securely and ethically.
AML Automation for Financial Institutions
The global AML market size is projected to grow to USD 9.38 billion by 2030 at a CAGR) of 17.8% — selecting the right AML software in this environment means looking beyond buzzwords. The evaluation criteria should center on adaptability, scalability, and explainability. Does the platform support multilingual, multi-jurisdictional compliance? Can it be deployed as a white-label solution for fintechs or integrated seamlessly into existing digital ecosystems? Is it continuously learning from transactional behavior? The best AML compliance software in 2026 will not be static—it will evolve alongside the threats it combats.
The companies that adopt a unified AML solution platform for banks & fintechs—backed by explainable AI, cross-module orchestration, and secure scalability—will not only meet compliance standards but exceed customer expectations.
By the time the next wave of regulations arrives, institutions that invested early in intelligent compliance will already be ahead. They will have built systems that learn continuously, adapt instantly, and protect both business integrity and customer trust.
The New Standard for Compliance Excellence
In 2026, compliance is no longer a checkbox—it is a strategic differentiator. Intelligent AML automation for financial institutions will determine which institutions thrive in an era of real-time, AI-powered finance.
Early adopters will operate with systems that learn continuously, respond instantly and withstand regulatory scrutiny—protecting both institutional integrity and customer experience. FlexComply’s modular, intelligence-driven design reflects this vision, empowering financial institutions worldwide to reduce compliance risk, strengthen regulatory trust and protect their brand reputation with confidence. To learn more visit flexcomply.flexm.com.

Singapore has evolved into one of the world’s most advanced fintech ecosystems — where technology, regulation, and innovation work hand in hand. As financial institutions look to scale efficiently, the modular fintech platform Singapore model has become the go-to foundation for growth. It allows banks, money service businesses (MSBs), and startups to build agile infrastructures that adapt to their needs. As a leading global fintech conglomerate, FlexM is at the forefront of this transformation — enabling institutions to unify compliance, payments, merchant acquisition, remittance, and business finance under one modular ecosystem that’s both secure and compliant.
The Evolution of Modular Fintech Platforms in Singapore
The demand for agility and interoperability is reshaping how financial systems are built. Modular and API-first architectures are now seen as essential for sustainable growth. According to a global banking technology report, 64% of banks worldwide are moving toward modular or headless architectures to boost speed, flexibility, and innovation.
The modular fintech platform model breaks down complex financial systems into manageable, scalable components. These modules — whether for onboarding, compliance automation, or payment orchestration — can be independently deployed and updated. This structure shortens product rollout times, reduces maintenance costs, and ensures operational resilience — key priorities for Singapore’s digitally driven financial institutions.
Singapore’s progressive regulatory framework has also played a pivotal role in promoting this transition. Initiatives from the Monetary Authority of Singapore (MAS) have encouraged collaboration between traditional banks and fintech innovators. As a result, modular and open-banking approaches have flourished, helping institutions stay compliant while experimenting with new technologies like AI-driven compliance, cloud-based remittance, and digital payment systems.
Scalability: The Core of Modern Financial Infrastructure
In the modern financial environment, scalability is no longer a technical feature — it’s a strategic advantage. As financial ecosystems become more interconnected, institutions must ensure their platforms can handle increasing transaction volumes, diverse regulatory requirements, and multi-market operations without compromising performance.
A modular fintech platform Singapore model supports this by allowing institutions to scale seamlessly in both capacity and capability. Whether managing higher transaction throughput, onboarding new partners, or expanding into new jurisdictions, scalability ensures systems grow in step with the business — not ahead of or behind it.
What sets scalable architecture apart is its resilience. Modular and API-driven systems are designed to absorb change smoothly, adapting to shifts in compliance, customer behavior, and emerging technologies. This future-proof approach ensures that financial institutions stay competitive, even as new fintech entrants and digital-first banks reshape the landscape.
For Singapore — a hub that processes billions in digital transactions annually — scalability also strengthens financial stability. Institutions that can adapt quickly to growth opportunities and regulatory updates remain better positioned to serve global markets while maintaining the operational reliability that the country’s financial reputation is built on.
Why Banks, Startups, and MSBs Prefer Modular Systems
For banks, adopting a modular banking platform Singapore model offers a strategic path to modernization. Rather than replacing their core infrastructure entirely, they can introduce new modules — such as compliance management, digital payments, or risk monitoring — step by step. This gradual integration minimizes risk while boosting efficiency.
For startups and MSBs, modularity offers scalability without complexity. With pre-built modules for remittance, merchant onboarding, compliance, and payments, they can launch quickly and adapt as they grow. This democratizes access to advanced financial infrastructure, allowing smaller firms to compete effectively with established players. Singapore’s fintech ecosystem — home to hundreds of innovative companies and global partnerships — demonstrates how modular systems are becoming the standard for efficiency, security, and trust in financial operations.
Building the Future of Financial Infrastructure
As the financial world continues to expand through strong collaboration between regulators, banks, and innovators. Open APIs, sandbox environments, and data-driven partnerships allow institutions to integrate new modules faster than ever before.
The modular fintech platform Singapore concept is redefining how institutions collaborate and compete. Cloud-native APIs, AI-driven compliance tools, and real-time analytics are helping businesses stay ahead in an increasingly data-driven world. This shift aligns with the fintech platform for banks Singapore approach — where flexibility, security, and transparency coexist to drive innovation.
Conclusion: The Future Is Modular, Scalable, and Compliant
The modular fintech platform Singapore model has become the cornerstone of financial modernization. By leveraging modular design, institutions can innovate faster, stay compliant, and operate globally without friction.
Leading fintech players like FlexM exemplify how a modular fintech platform can merge innovation with integrity — integrating compliance, payments, merchant acquisition, remittance, and business finance into one powerful, scalable solution. As Singapore continues to set global standards for fintech excellence, the modular banking platform Singapore and fintech platform for banks Singapore approaches will remain central to its vision of a truly connected, compliant, and competitive digital economy.


Where We Made the Difference
The solution was devised as not only a way to embrace digital but also to create a unique model to offer cashback at offline merchants. This enabled the offline retailers to match their online shopping counterparts in creating customer loyalty by integrating proven contactless solutions.

The Agrani Remit app is an excellent example of how digital innovation helped the Bangladeshis working in Singapore to digitally and conveniently remit money, back to their family members safely…

FlexM, one of our collaborative partners, played a crucial role in conceptualizing the solution (FlexM's Compliance Solution). Their continued support throughout this transition has been invaluable. We are grateful for FlexM's significant contribution to the solution and their unwavering support as we navigate this transition.

FlexM offers invaluable (RegTech) services for monitoring our card transactions and reporting to the RBI. Their expertise and commitment to excellence have significantly enhanced our compliance and risk management processes.