

Building the Fintech Dream


The Latest Content
The fintech chant that started as a tiny whisper, can now be heard resounding in almost all corners of the world. What’s more is that this chant is now being accompanied by drums and trumpets, owning its presence and how! The innovation spree in this industry has been the mainspring of this revolution, where companies have created and recreated technology that has made the world a lot smaller, in a good way.
However, with such galore, comes raving competition.

Highlights in Southeast Asia’s Fintech
The CAGR of fintech is reportedly perched up at a stupendous 25%, rendering it to be the fastest growing industry today. In 2020 alone, the US had 8,775 fintech start-ups. By 2021, the number of start-ups had gone up to more than 11,000 in America, 6,500 in the Asia Pacific, and almost 9,000 in EMEA.
The Asian fintech market has witnessed a leaping progression in recent times, as some of the biggest players are rooted right here. Alipay, owned by Ant Financial in China, is the global leader in fintech. What started as simple eWallet solutions, has now transformed the face of fintech and found its niche in people’s everyday routines. They offer ePayment solutions, wealth management, investments, eBanking, international payments, and much more. With a vast network of operations in 40 countries, Alipay has claimed the position of the world leader in this industry.
Talking of leaders, the UK has been at the forefront of fintech globally; London becoming the hub, with the highest fintech index, closely followed by San Francisco and New York. In Asia, the fintech market has found its pivot in Singapore.
Singapore City is a financial fulcrum, and it is no new revelation that it is one of the leading fintech cities. More than 40% of Asia’s fintech are based here and the funding of fintech start-ups has multiplied by more than three times in the past 5 years.
Grab, the leading fintech giant in Southeast Asia is an amalgam of delivery services and payment solutions. It has expanded its operations across several countries including Singapore, Indonesia, Thailand, Malaysia, and more. Its service suite, which started as simple food delivery, has now branched into finance and payments, which include lending and investments too.
For Visa clients in Singapore, a partnership between Railsbank (London) and Visa has prompted the enablement of visa payment technologies, allowing easy on boarding along with spectacular fintech benefits and access. Now, clients in Singapore can avail of Railsbank services too.
India has not been far behind in this pyramid of fintech leaders. The consumer shift towards fintech in India has been parallel to that of China, with both countries reporting an 87% shift into digitalization. The Indian cities of Bangalore and Mumbai have exponentially grown vis-a-vis fintech.
Razorpay is the key player in India, which allows businesses to process payments with its elaborate suite. Founded in 2013, with a solution-driven focus, the company has received total funding of more than $750M USD which has powered its aggressive expansion. Paytm, another fintech in India has become the most reliable and used e-payment gateway for the enormous Indian population. With a revenue of almost $420M USD, this company too is charging ahead in the race.
Indonesia has attracted quite a big chunk of fintech funding, making its presence unmissable in this market. The GoJek digital payment solution has transformed into a lifestyle platform, allowing users to book taxis, order food, make digital payments to other vendors, etc. GoJek is a well-established fintech organization, competing with the likes of Rapyd (London) and Affirm (San Francisco).
The Thailand fintech market also has been in the news with its e-payment platform, PromptPay. The fintech platform that allows easy payments using personal data for verification purposes, has recently tied up with Rapyd, the London-based fintech, that has launched PromptPay services on the Google Play Store, enabling Thai consumers to install the app and make in-app purchases with ease.
Hong Kong too has found a place among the top fintech hubs in the Southeast, followed by the Malaysian capital, Kuala Lumpur. Immunity from Covid?
While Covid-19’s fatal impact echoed all over the world, affecting all segments and countries, especially in terms of finance, Singapore’s destiny was earmarked for gains. Investors took particular interest in the potential scope of Singapore’s finance market, fueling its engine with private investments. The businesses that started off as simple e-payment solutions and quick personal loans have branched out into a wide array of services, including investments, wealth management, payment and remittances, reg-tech and data analytics, and more. Owing to the market being emergent still, the majority of Singapore fintech start-ups are in the early stages of business. 70% of the start-ups have thrived on Seed or Series A investments.
Closing WordsThe fintech fraternity in recent years has witnessed an uprising like no other industry. While the UK and USA lead the way today, the extent of innovation and consumer shift seen in Southeast Asia remains unmatched. The engine has just caught its momentum, if fueled right, the market dynamics here might just thwart forward and acquire reign eventually.

The potential of technology has emerged as a majestic superpower that we are increasingly dependent on in today’s world. Everything, or almost everything, revolves around these two words – finance and technology; the leading elements of this new age world, which symbolize the monumental scope of all that we can be and achieve.
Fintech, our shining star, has taken the helm of the structure of finance in these modern times. From purchasing products overseas, transferring money from one corner of the world to another, to making virtual and cashless transactions from personal mobiles, everything has become possible and easier, under Fintech.
And if there is one sector that was propelled forward during the pandemic, it is Fintech. Staying at home, and going cashless to avoid physical transfers between people, brought a compelling surge in this field.
Fintech hubs worldwide are booming with innovative technology and are disrupting banking like never known before. Read on to find out more about the prominent trends in this space.

Neo-banks
Neo-banks are digital banks which exist only online entirely. This particular type of banking has been one of the major disruptions in the traditional banking sphere, because of negligible human interaction, allowing users to avail all kinds of banking services from any corner of the world with user-friendly interfaces.
This concept has widely been adopted by new and old institutions alike, where digital banking services like money transfers, account opening, KYC, and many more services are given as an extension to the prevailing ones.
Robotic Process Automation
An augmentation to digitalization and automation, RPA – Robotic Process Automation involves employing robotics or digital employees to work in place of humans to make several processes more efficient and increase accuracy.
The primary intention of engaging RPA in systems is to increase efficiency and cut down on costs which enables the RPA employers to focus their time and resources on improving customer services.
Blockchain
Blockchain technology has intrigued the financial sector because of the blanket of security that comes with it. This Avant Garde technology disrupts the centralization of procedures, making it possible to store data in a decentralized space, which is almost impossible to falsify or manipulate.
The level of security that comes with this innovative technology makes it possible to conduct transactions overseas safely, which is immensely appealing.
Artificial Intelligence (AI) & Machine Learning
These prodigies of innovational technology have introduced us to the multitude of possibilities that can transpire when the human mind gets creative. Chatbots, market trends analysis, flawless cyber security, credit and loan resolutions, and customized services are just a few of the many breakthroughs that have materialized because of AI and machine learning.
As more and more processes corroborate with AI, the extent of identification and protection against cyber threats remarkably increases and the operational costs of financial institutions go down substantially, making AI an indispensable pillar.
Biometric Security Systems
An extension of AI, biometric security systems are the coming of age of the brilliant concept of substituting signatures with more definite and secure options like fingerprints, facial and iris recognition, voice analysis, etc.
This brings the structure of financial security to an altogether new pedestal, where personal information is corroborated with biometrics to create fool-proof cyber safety.
Open Banking
This is the space where banks can join hands with third-party service providers, with the help of application programming interfaces (APIs) to enable transferring data and services between customers, banks, and third parties.
For instance, a customer could allocate powers to a third-party app to make transactions using their bank accounts which makes payments, standing instructions, and connections much easier and more convenient.
Regulation Technology
In this, technology is heavily employed to handle and monitor regulatory compliances, which enables systems to act in accordance with compliances, that could otherwise be omitted due to human error. Reg-tech versatility allows the same institution to adapt and change technologies according to jurisdictions and locations.
Gamification
Inspired by people’s fascination to get rewarded, financial institutions also have joined this corner, where they apply gamification strategies to engage their customers. The most prominent technique has been to give rewards based on transactions and the value of the customers. Some institutions also provide scorecards and/or badges when customers complete a particular task, like making 10 transactions using the bank’s app in a month.
Gamification has enabled a more profound engagement between banks and customers, where banks analyze and read the customers’ actions and provide incentives accordingly.
Final Thoughts
The emergence of Fintech started with tiny steps a little after 2012. Ever since then, the momentum of its expansion and adoption has only increased worldwide. Today, there are more than 26,000 Fintech start-ups bridging gaps and innovating relentlessly to make financial services easier and safer. Around 30% of traditional banking customers have adopted and received financial services from third parties and the number is only rising every day.
It would be appropriate to say that the storm of Fintech is not here to settle.

Singapore has always been known as the financial hub of Southeast Asia because of the idyllic, opportunity-laden environment it provides. In recent times, with the upsurge in the world of Fintech, the country inevitably has witnessed marvelous evolution in this regard too. Startups and companies from all over the world have been turning to Singapore to find a spot vis-à-vis Fintech incubation or business tie-ups.
Based on a number of reports, Singapore has been ranked as the 4th largest financial hub in the world after New York, London and Tokyo. The economy of the country is thriving. When it comes to Fintech, Singapore’s economy has witnessed even more success. To prosper amidst such high levels of competition and come out as a world leader, requires some prerequisites. The three main elements that have been identified as essential prerequisites to become a Fintech hub are – the number of entrepreneurs initiating startups, an investor’s pool to fund the operations and growth, and education and expertise. These help lay the basic groundwork for an economy to head into the direction of becoming a Fintech leader.
But there is a lot more involved when it comes to being a world leader in Fintech. For the entire ecosystem to flourish, a strong financial backing, combined with expertise in innovation and technology is absolutely imperative. To achieve these, the environment has to have the right kind of opportunities and support. The next section explains these prerequisites in a more detailed manner.

What Does It Take to Become a Fintech Hub?
A report by ICAEW has correctly identified five elements that converge to make a Fintech center. These five elements are:
Expertise
Knowledge and expertise form the base of success in this domain. The world of Fintech relies heavily on innovation and creativity. When there is adequate education and available information, it leads to opportunities. These opportunities are tapped by budding entrepreneurs, which creates competition, which in turn opens doors to a revolution. Technological and financial expertise and knowledge is essential in reaching the top tier of Fintech.
Investment
Capital investments are what breathe life into these innovations and businesses. The world of Fintech is being led by startups, which don’t have adequate funds to create what they aspire. This is where the role of investors comes in. With money flowing in, it is possible to expand operations, hire experts, and grow. Growth of a startup hugely depends on the level of its funding.
Consumers
A ready market with huge demand and consumption, completes the circle of a startup delivery. The customer is what makes it possible to make this process an ongoing one. This is where the startup can make its choice of whether it intends to cater directly to the end consumer (B2C), or if it intends to partner with other businesses (B2B).
Regulations
With the growing number of possibilities of innovation, it is crucial for an economy to lay its focus on regulating the operations of all the booming businesses. A competitive market leads to innovation, but if unchecked, it could also lead to several misdemeanors putting the customers or the startups at risk, which could ultimately lead to a downfall.
Government
A befitting government support to manage investments, and the market, is one of the key factors which governs the success of the economy. The layout the government has planned for business operations plays a huge role in determining how all aspects of the economy would function.
These five elements have been identified as the key to becoming a Fintech power. These make a common framework in all the leading economies in the world. The instances of London and Singapore both were analyzed and compared to understand what underpins successful Fintech hubs.
Singapore: An Overview
Singapore, with a population of only around 6 million, has achieved an exemplary feat in the Fintech space. A huge number of Fintech startups have come up in a short span of time, delivering services and products which are in direct competition with their counterparts in bigger economies like the United States and the United Kingdom. Such enablement has brought the world’s focus on this small island city-state, which proudly stands with its head high.
Unlike the counterparts in New York and London, everything about the Fintech space in Singapore is quite different as it is focused overseas.
The country is surrounded by much bigger markets in Southeast Asia, where there is an exponential potential waiting to be tapped. A majority of the startups in Singapore are targeting collaborations with banks in other Asian economies. With this approach, it is aiming to become an indispensable Fintech partner which helps bridge the gap between conventional and digitalized banking.
Singapore’s Fintech sector has been dominated by e-payments and remittances startups being the first Fintech products in general, but now, with new branches in Fintech like cyber security, regulation technology, etc., the shift in focus has started diluting this dominance, giving space to more diversification. This in turn, has led to a substantial increase in investment opportunities.
Overall, the Fintech ecosystem in Singapore has proven itself perfect. Finding and tapping on the right opportunities and making itself an indispensable aid, is what is giving Singapore new heights. With innovation booming inside, and investors pouring in from the outside, Singapore becoming a Fintech magnet only seems predestined.

Fintech, short for financial technology, is that stream of business that challenges long-established ways of banking and finance by using innovation and technology to spearhead a financial revolution. We have come a long way from traditional banking, where the protagonist’s role was played by cash and other physical commodities, to the present where a majority of our financial activities have transcended into the virtual space of the internet.
And that is precisely how Fintech has taken the world for a spin by providing options like easy money tracking and management, global payment options, quick loans, excellent customer service, and much more. The limitless world of Fintech has surpassed the older notions of only engaging with financial institutions and has branched out into several sectors, including cryptocurrencies.
I think it is safe to say that the world of finance has witnessed an evolution almost as remarkable as mankind itself!
Fintech as a Service (FaaS), as the phrase suggests, means- when a company develops financial technology to sell it as a service to other companies. This allows companies that don’t originally have technological leverage, to equip their systems with Fintech that could either be used in-house or externally or in both ways.

How Does This Work?
FaaS has emerged as the prodigy that everyone either wants to parent or employ. Owing to the wave of competitive creativity in this field, we have been able to establish a broad spectrum of FaaS applications.
To enable these innovative capabilities in FaaS, Fintech servers mainly develop and employ APIs (Application Programming Interface) that bridge the technological gaps, allowing the delivery of these services. The Fintech server embeds its APIs in the client’s existing applications, which enables the client to fuse their products and services with the Fintech server’s technology, making way for new methods of serving customers.
These services range from e-wallets, KYC (Know Your Customer), new account openings, managing remittances, transaction tracking, identity verifications, card issuances, and global payments for the management of the client companies’ financial operations. With a reinforced focus on customers, the company can also provide more customer-oriented services to its customers like customized transaction reports, flexible standing instructions, and 24*7 customer service.
With FaaS in place, it has become possible for companies to function without investing in any infrastructure, focus on consumers, and most importantly, they are able to integrate and curate existing dissembled financial services in a much more systematic and easier fashion.
What Benefits Does FaaS offer?
Apart from empowering companies to gain traction as Fintech, there’s a lot more that FaaS offers:
Opportunity for Low Investment: A company’s investment is substantially lowered when it opts for FaaS from a third party. It can evade setting up a dedicated infrastructure, acquiring licenses, hiring developers, conducting trials, and even maintenance of the system, as all of this would be taken care of by the third party. What’s even more lucrative is that the companies can reduce their operational cost by choosing providers that suit their budgets.
Incredible Flexibility:The scope of agility in FaaS is enormous, which is also the underlying reason behind its success. With FaaS, the range and timeliness of services offered at traditional banks can be propelled to a different dimension altogether. Easy identity verification, one-click loans, and payments, frictionless customer service, and effortless international payments, are some of the many services that can be offered by a company that is fueled by FaaS.
Secure Setups: Instead of going through the trouble of acquiring licenses, to set up independent gateways, the company can opt for a FaaS supplier with these prerequisites, which would give them a thick layer of security. With secure APIs in place, not only would the company be secured, it would also make the network much safer in comparison to every company developing its own Fintech.
Timely Results: With the third party taking the helm on the technological front, the time taken for a company to launch their Fintech services is considerably reduced as they don’t have to start the entire process from square one. Once they are technologically equipped, they can start off immediately, without conducting market trials, saving a lot of time and resources. Since the third party is also going to look into the maintenance sector, the company doesn’t need to allocate any resources there as well.
Customized Services: FaaS platforms allow incredible space for customization. They allow the company to keep its voice and look, by only taking charge in the backend. This way, even if the company is remodeled, the changes in the backend will only have a more pronounced reflection of the company in the front.
Fintech Trends
The origin of Fintech has witnessed marvelous step-ups, and it is only recently that the world has started realizing the tremendous scope that this possesses; the path to future-proofing.
According to the Financial Express, the Fintech market is all set to reach an estimate of $310 billion in terms of investments. This colossal valuation has been estimated to be almost double what it was in 2018. The other new shoots like cloud computing, neo-banking, blockchains, and e-commerce in this industry, which share a taut relationship with Fintech are also going to witness an insane jump.
I think we could all agree that equipping companies Fintech-ly is the new black.

Electronic Payments, more commonly known as e-payments are digitalized payment solutions, offered by and on behalf of banks by in-house setups or third parties. The evolution of payment solutions has witnessed a steep rise in terms of innovation and adoption. These convenient, user-friendly solutions have been created in a way to suit the seller and the consumer both.
The e-payment solutions are not limited to only making payments for purchases, by virtue of their adaptability, they are now being used for top-ups, payments to and from banks, cross-border payments, and many more. Digitalizing payments has disrupted conventional methods of making transactions, by bringing simple and convenient alternatives to handling cash.
The quality that has helped revolutionize e-payments is the level of convenience that comes with it. 3 out of 4 people exposed to the workings of the digital age are adopting electronic solutions to keep up with the rapidly increasing changes, and to improve connectivity worldwide.

Benefits of E-Payments
An organization’s online presence and dominance govern how it is perceived by the masses. The more innovative and easy solutions the organization provides, the more customers and in turn investors, it can attract. With the growing number of people switching to digital platforms for conducting transactions, it has become essential for banks and third parties to offer solutions that their customers can relate to. There are several benefits of providing and adopting e-payment solutions.
Omniscient Presence
Digitalization has immensely disrupted the normal everyday things in our lives, in a good way. The aggressively increasing popularity of e-payments has mandated banks, vendors, and third parties to offer these options to people. Because of this, we can now find these options and solutions almost everywhere.
Quick Turnaround
e-Payments happen in real-time. Unlike conventional methods, digitalization has enabled quick transfers and transactions, which otherwise would take several days. Solutions like fast air-time top-ups from anywhere have increased their popularity.
Simpler Processes
Apart from being quick, digital payments are much simpler and easier to conduct. The customer does not have to go through the trouble of waiting for a week to get their cheques cleared.
When simple procedures combined with user-friendly interfaces are made available, no one would want to go back to conventional, time-consuming, and complicated processes.
But with every asset comes a liability. As is the case with e-payments too. With growing connectivity, digitalization, and countless possibilities, there are risks and expenses to consider.
The Challenges
e-Payments is one of the products borne out of the amalgamation of finance and technology – Fintech. The risks and challenges that can potentially hinder the smooth functioning of these can be subdivided into two major categories- risks specific to the finance section and the challenges associated with the technological segment.
Financial Risks
Security Regulations
Innovation and creativity require a free hand and space to experiment and grow. But, without regulations and discipline, the entire space would become extremely risky. Providing secure gateways to conduct payments and transfers is mandatory and even a minute slip can cause colossal damage.
Authentication
One of the most common methods of providing e-payments is for a Fintech server to partner with a conventional institution to back the latter’s financial services with technology. In this method, it is crucial to have mutual authentication by both parties before processing an online payment. Authentication of the user or the device helps in developing a fool-proof system for payments to go through.
Data Privacy
Financial information of the user and their dealings are very sensitive in nature. The security system to protect this type of data requires advanced techniques. With the growing ease and frequency of making payments on miscellaneous websites, users are given options of saving their financial details, like their card numbers and expiry dates to enable quicker payments. When this type of sensitive information is saved on the internet, the financial institutions and the third parties are partly obligated to protect the information and the user from falling into the hands of malicious activities.
Technological Challenges
Adaptability
With the growing presence of Fintech worldwide, one of the primary objectives of Fintech servers is to make their system and infrastructure such, that they can adapt to different requirements and setups. The modernization in this domain has to be compatible with conventional methods too, as digitalization cannot completely replace the conventional methods. The intention of digitalization shouldn’t be to override other payment solutions and methods.
Easiness
Easy and simple processes act like Pied Pipers, pulling everyone towards them. With the majority focused on seeking convenience and user-friendly interfaces, it becomes a challenge for Fintech servers to simplify their procedures further at such a competitive rate. Simple and reliable e-payments form the base of everything that a consumer is looking for.
Other Challenges
Expensive
Digitalization demands fierce advancements and innovation in technology which involves extensive procedures, hiring experts, and producing intelligent results. This entire process becomes expensive. With the growing demand and competition, the Fintech servers perpetually need to be on the lookout for methods to save on their costs to bring down expenses.
Network-dependent
e-Payments are network-dependent. Even though they are highly convenient and marketable, areas with little or no network cannot accommodate digitalization. This is one of the major obstacles which hinder the growth of e-payment solutions.
Country Laws
When it comes to overseas e-payments, it is mandatory for Fintech providers to abide by country laws in the countries they are offering their services in. Not abiding by these laws may lead to their services being terminated.
Overall, the upsurge in the number of Fintech start-ups all over the world has changed the face of digitalized payments. With more and more people adopting these solutions, it has become crucial to regulate how Fintech operates. Data protection and privacy along with much-needed versatility, have poured in countless obstacles and hindrances. It is up to the Fintech industry to bring its game up to a level where anyone from any corner of the planet can make quick and secure payments, at any time.

A recent concept, now in practice, neo-banking has brought a revolution in the banking industry. From traditional banking methods to digital banks and wallets to neo, the concept of finance has transformed significantly. Technology in every industry and sector has gained tremendous momentum in recent years, and the same rhythm can be felt in the financial world too.
Neo-banks are institutions, which provide financial services similar to those of traditional banks, the only difference is that these services are strictly only online. They entirely exist digitally. Fintech has made it possible for us to get banking services online, without there being any physical branches. With easier processes, user-friendly interfaces, and lower fees, the banking system has witnessed quite a remarkable makeover in recent years.

Neo-banking Vs. Traditional Banking
There are quite a few distinctions that can be drawn vis-a-vis the different setups and services. Neo-banks may or may not possess the license to function as independent financial institutions. Many countries have granted permission for independent licenses, but many countries like India, are yet to follow the trend. They provide services similar to those of traditional banks, but because of their regulatory limitations, the services offered by neo-banks are not as holistic compared with the traditional ones. Their services are much quicker and their fees are much lower, which gives them scope for a much wider acceptance and audience.
Neo-Banking Vs. Digital Banking
Digital banking is a component of traditional banking, like an extension, or a service provided by regular banks. Neo-banks on the other hand, are majorly fintech companies or start-ups, which function independently. Neo-banks leverage technology to provide customized and quick services to their customers using artificial intelligence and data insights.
How Do Neo-banks Function?
If neo-banks are granted independent financial licenses, they exist as their entity. However, if they cannot possess licenses, like in the case of neo-banks in India, they usually form tie-ups with traditional banks, where they provide the technology, and their partner bank provides the products and services. Traditional banks too could have their neo-banks.
Benefits of Neo-Banks
User-friendly and Easy Processes
With a heavy focus on making interfaces as user-friendly as possible, one of the biggest advantages neo-banks offers is simple processes and procedures. Their services are much more convenient for users, as there are lesser restrictions in terms of time and effort, for instance, a user can have their KYC (Know Your Customer) done sitting in the comfort of their homes.
Augmented Customer Services
One of the core objectives of neo-banks is enhanced customer services. The entire concept of omitting physical branches and reducing human interaction aims to amplify the customer service segment. With the target of disrupting conventional banking methods, neo-banks create easier and quicker processes to provide intensified customer-centric services.
Quick Services
The turnaround time for transactions, registrations, and services like new account opening is negligible, making it much more convenient for users to systematically manage and operate their finances.
Lesser Costs
Because neo-banks only exist online, they save a lot on the cost of infrastructure. With lesser human involvement and no physical structure, these banks can offer more services at lower costs.
Disadvantages of Neo-Banks
Financial information and activities are sensitive and even slight negligence can lead to immense damage. With digitalization making the entire world accessible to everyone, neo-banks are compelled to abide by the different regulations and rules in every country they operate in.
Limited Accessibility
Even though technology has advanced substantially in developed nations, many corners of the world are yet to experience the wave of digitalization. With countless potential consumers still anticipating experiencing this revolution, neo-banking faces limitations when it comes to inefficient basic infrastructures.
Limited Services
As digitalization in many aspects is still a recent phenomenon for the majority, there are strict regulations and limitations which hinder the smooth functioning and expansion of neo-banks. This ultimately limits the scope of services they can freely offer.
Future of Neo-banking
Globally, the neo-banking industry has reported a CAGR of 51% since 2017. With the number of users shifting to digital modes of banking, this number will only grow. In 2021, the valuation of neo-banks globally was reported to be a little less than $48 billion. Judging by the exponential number of start-ups emerging in this sector of fintech, the valuation is estimated to grow by more than 50% before 2030.
The Indian market mainly has been in the limelight as the number of smartphone and internet users in the country is one of the highest in the world, making the ecosystem there extremely habitable for the future of fintech.
Neo-banks are already starting to be perceived as alternatives to traditional banks. With countries making regulatory changes to increase allowance and acceptance for neo-banking, the picture looks bright when it comes to the future of neo-banks. More and more start-ups focused on neo-banking are emerging every day. As the market is filling up with new neo-banks, the intensity of competition has grown remarkably, resulting in more innovation and better services.
The future of traditional banking is not in jeopardy as they cannot be replaced completely by neo-banks for many reasons like the mass majority is still not very familiar with new technologies changing the face of banking, neo-banks cannot substitute human involvement for services that require them, etc.
Neo-banks have provably disrupted traditional banking methods. Both new and old techniques are targeting partnerships to not only help bridge gaps but also enhance their services. With the extent of possibilities that are rapidly materializing by corroborating finance and technology, it is only a question of time when neo-banking will be as popular as traditional banks.


Where We Made the Difference
The solution was devised as not only a way to embrace digital but also to create a unique model to offer cashback at offline merchants. This enabled the offline retailers to match their online shopping counterparts in creating customer loyalty by integrating proven contactless solutions.

The Agrani Remit app is an excellent example of how digital innovation helped the Bangladeshis working in Singapore to digitally and conveniently remit money, back to their family members safely…

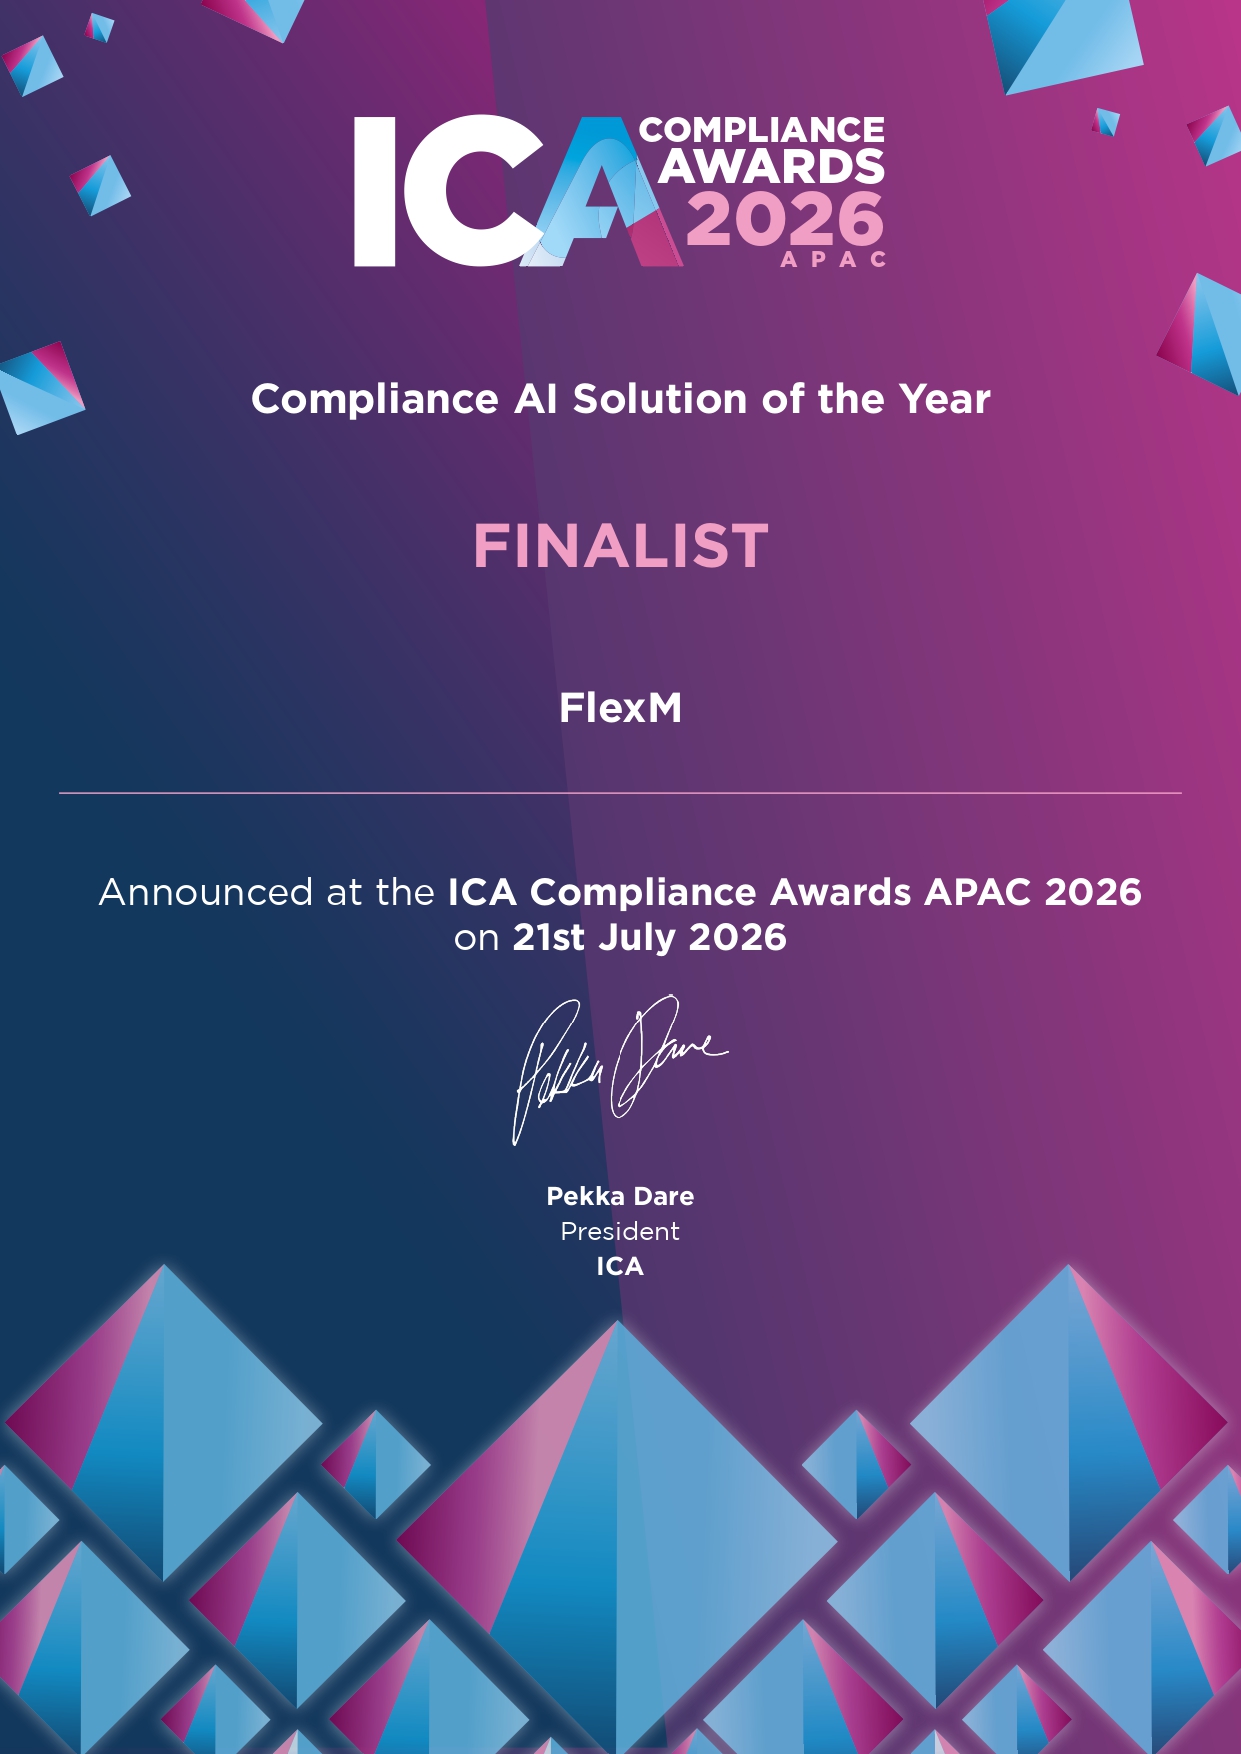
FlexM, one of our collaborative partners, played a crucial role in conceptualizing the solution (FlexM's Compliance Solution). Their continued support throughout this transition has been invaluable. We are grateful for FlexM's significant contribution to the solution and their unwavering support as we navigate this transition.

FlexM offers invaluable (RegTech) services for monitoring our card transactions and reporting to the RBI. Their expertise and commitment to excellence have significantly enhanced our compliance and risk management processes.