

Building the Fintech Dream


The Latest Content
Compliance, a buzzword in the fintech industry is keeping all fintech firms on their toes. With the advent of fintech services and their global adoption, all in the last recent years, the risk of cyber security getting comprised has become high.
Cyber threats and malevolent agents have become a prominent risk in the system. The level of advancements in fintech development is impressive. However, talent isn’t restricted to the good side of fintech. With advancing technological developments shaping the fintech industry, the level of technology being employed by hackers and malicious parties is immense.
To tackle this level of noise and intrusion from unwanted parties, regulatory bodies of the fintech world have become increasingly active and robust to match pace with the dynamics of fintech.

Background of Fintech Regulations
- According to a report, there were approximately 220 compliance revisions that fintech firms had to manage daily.
- Since the onset of globalization back in 2009, the total of regulatory fines imposed on financial institutions and firms has exceeded $345 billion for different reasons.
- The average cost of fintech compliance has risen exponentially and is still rapidly rising.
RegTech
An amalgamation of regulations and technology, RegTech is a crucial subset of fintech, which helps monitor advancements and activities to increase efficiency and safety in the entire system. RegTechs are technology firms that provide technological services to traditional financial institutions and fintech firms that help simplify compliance and regulatory procedures with the help of digitalization.
This subset of fintech has increased prominence and importance because of its supplementary nature of services which makes the entire system more efficient and effective. RegTechs use top-notch technologies that keep track of relevant international and country-specific compliance regulations and consequently, help the customer firm to tweak their system and procedures in such a way as to avoid any breaches and lags.
The use of technology to facilitate regulatory conformities has produced a revolution, rendering it a world of its own. RegTech promotes technological advancements to monitor internal as well as external activities, increasing security considerably and protecting the customer.
Main Technologies Supporting RegTech
With enormous amounts of data pouring in every minute of every day, companies have had to succumb to technology and automation to manage and make sense of it. Analyzing trends, customer reports, company assets, and financials, becomes achievable when such complex processes are supplemented by technology. The main technologies that support RegTech are:
- Artificial Intelligence & Machine Learning
- Blockchain
- Cloud Computing
- Application Programming Interface
- Visual Analytics
The Future of RegTech
Owing to the mass adoption of fintech and the dynamism in the industry, regulatory practices have become a must for every subset instrumenting its role in fintech. RegTech has gained popularity because of the convenience it brings to all parties; regulatory bodies can keep better control even at the international level, startups can ensure all their activities are following all relevant compliances, etc.
The level of investments in RegTech has spiked by a huge margin in the past five years. This industry’s growth directly correlates with the fintech industry. As more and more fintech startups bring dynamic technological developments to the fintech world, the need for regulatory compliance and monitoring will only increase.
Thick files and folders containing hundreds of international and country-level regulations make it essential to streamline the regulatory system. Any miss or gap in monitoring can cause damage to a large extent. The level of investment that it takes for firms to deal with such issues is immense. But the potential cost that a company could incur on non-compliance with any of its activities would be much greater.
Companies have spent billions of dollars to streamline and monitor regulatory compliances. By 2022, the international regulation management market was expected to reach more than $200 billion.
Such extravagant costs have the potential to stub the market growth of RegTech as well as Fintech. However, relentless efforts are being made globally to minimize costs as much as efficiency and effectiveness allow.
The Purpose of RegTech
RegTech has two primary purposes:
- Regulating and monitoring fintech activities across the world according to regulations that have already been established in the past
- Continuous evolution and adaptation of new fintech trends and innovations that are emerging every day
Closing Words
RegTech is an inevitable subset of fintech that has made its position at the core of the industry. With changing and exhaustive guidelines making rounds globally, it has become an impossible task for financial institutions and fintech firms to not get technological supplements. RegTech helps simplify extensive processes by using various technologies to bridge the gaps between specified standards and industry practices.

Data privacy in broad terms means the protection and security of data and information regardless of their nature. The internet is an infinite space with the potential to store unimaginable amounts of data. Every time a user conducts a small Google search, every detail of the process is stored in the form of data by the websites that are involved in the process, including Google.
With uncountable opportunities for companies to acquire information, it becomes crucial for the system to be regulated and monitored. Data privacy is the practice of protecting all types of information, especially that which is sensitive in nature, like personal details, financials, and intellectual property data, from becoming mistakenly accessible to any malicious agents.
The most important aspect of the virtual world is data. The majority of cyber activities prevalent in the world today have found their origination and ideation from data. Information can be segregated into different segments like personal information, company information, information related to purchases, employees, stocks, future projections, etc. Anyone having access to restricted information can put the vulnerable party at stake, be it a company, an individual, or even the government.
The importance of data was not so pervasive till a few years back. With the onset of computers and smartphone technology, the amount of data that can be stored and used has led to data becoming one of the most indispensable assets there could be.

The Leverage
Information of all kinds has earned the position of a crucial requisite in recent years. Companies store and use customer and visitor data to analyze trends, behaviors, and habits to get psychological insights, which they can then use to their advantage.
Individuals ordering pizzas every day from a local store would start receiving incentivized communication from either the pizza company, the platform that the individuals use to place the order, or both. Such scenarios directly indicate that companies store and use information about their customers to their advantage.
Using data in similar ways is a common global instance that most of us would have experienced at some point or the other. Sharing information about habits and behavior might not directly have a substantial impact on individuals.
The leverage that information provides to the holder is enormous. Depending on the nature and extent of information and data available, the accessor can cause massive damage if not monitored.
Financial Information
Data about individual and company holdings, expenditures, assets, clients, etc., contains everything the entity is and has. Any access to sensitive data like this can have detrimental consequences.
The most commonly occurring crimes related to data and information are theft, blackmails, disclosures, and damage to their hardware and software systems. Hackers and malicious agents can break down systems and put the affected parties at colossal risk.
Cyber Security in Fintech
Cyberattacks in the digitalized financial world not only bring financial damage to customers, but they have the potential to completely defile a company’s reputation. Fintech companies are obligated to protect their customers’ data because malicious parties are inclined to misuse this information and they usually intend to get financial gains, by hacking into the company’s firewalls.
Security Practices Implemented by Fintech Companies
To protect customer information from getting compromised, it is highly imperative for fintech companies to monitor and regulate their system continuously. Other than regulations, fintech firms usually try and nip the bud by exercising extensive authentication protocols like:
One-time Passwords (OTPs) –
To conduct any financial activity, small or big, company systems send OTPs to the registered mobile numbers or emails of the account holder, which is to be entered into the system every time the customer intends to complete a transaction. This process provides additional safety to basic passwords and hidden usernames.
Regular Password Changes – Most fintech and online banking companies have mandated a regular change of passwords. Depending on the company, it may set up recurring timelines, which mandatorily prompt the user to change their password, enhancing their security even further.
Timed Login Sessions –
This practice is usually used for financial accounts, where customers are only allowed a particular timeframe to stay logged in, after the expiry of which they are compulsorily logged out. This method allows a much smaller window for malicious parties to hack into the customers’ accounts amplifying the security considerably.
Multifactor Authentication – This technology is not restricted to fintech and has gained a lot of popularity on platforms that require users to create accounts containing any personal or financial information. The procedure involved in multifactor authentication mandates the customer to provide two or three kinds of authentication; it could include a combination of security questions, OTPs, and regular passwords.
Final Thoughts
Cyber Security is an essential part of fintech because of the potential impact it could have in case of any lags in this regard. Both companies and their customers should be wary of malpractices involving data and information. Protecting personal and financial information are fundamental steps to securing the identity and financials of customers and safeguarding a company’s reputation.

The fintech industry has made incredible progress in the past few years. In the pandemic alone, we all witnessed an evident upsurge in the adoption of fintech by people globally. Because of the gigantic scope of technology, the fintech sector has attracted countless professionals and experts, who continue to work relentlessly to create innovative fintech solutions for customers and businesses.
With the rise in demand and the adoption rate of fintech, the number of fintech startups has grown astonishingly.
Fintech hubs like Silicon Valley, London, and Singapore have uncountable startups offering various fintech services to customers all over the world. The extent of innovation and dynamism in the industry calls for strict regulations.
Because of the ever-evolving nature of technology, compliance and regulatory standards have become a mandate for operating in fintech. With so many players in the market, there is a persistent possibility of risks like money laundering, hacking, etc., that could lead to immense damage. Therefore, the need for a robust regulatory system is a must.
More than anything, it is the scope of technology that is used and abused by criminals to beat the regulatory structure of the industry. To curb and mitigate the risks involved in fintech, all players in the industry would need to consistently work together to streamline processes and set up efficient systems.

The Risks Involved
Fintech is an increasingly dominating industry that is gaining popularity quickly. With businesses and customers adopting fintech practices all over the world, the possibility of data and information falling into the wrong hands, increases. The most commonly occurring risks involved in fintech are:
Money Laundering
Money laundering practices have been quite prevalent in the past and are still going on in the present age at a big level. Fintech enables the easy and quick transfer of money, especially transactions that require cross-border activities. If there is some level of leniency in the regulatory system, it could lead to the transfer of power from regulators to the people, leaving scope for anonymous and unverified transactions.
Quick Transfers
Fintech allows very fast transfers and transactions. Big amounts can be transferred across borders in a matter of seconds. This speed can also be used as an advantage by criminals. By quickly transferring big amounts from one account to another, there is the possibility that the trails created by these transfers outpace the regulations and scrutiny by the authorities.
Criminals target “money-mules”, who are vulnerable customers like elderly or disabled people, who would not have the resources or the robustness to manage their financials very efficiently.
Customer Identities & Data Privacy
As fintech operations and functions exist online, it leaves some space for anonymity that is exploited by criminals and hackers, where they can conduct transactions online by breaching companies’ customers’ data and filling in their information.
Criminals can also hack into company systems if there are regulatory lags and can steal personal and financial information of the customers or the company, putting everything at risk.
Bad Loans
Another risk involved in fintech is bad loans. With verification processes being conducted virtually, there is a huge possibility of people manipulating their data to get loans from banks, which then turn into bad loans. These bad loans make the entire system vulnerable and unstable.
Risk Management
With an innumerable number of players functioning in the fintech sector, the role of regulators has become indispensable. It has become absolutely essential for regulators to prioritize handling and mitigating the risks involved in fintech. Risk management is a vital tool for fintech companies that they should invest in. By following regulations and meeting industry standards, the possibility of risk exposure lessens.
Due to the changing landscape of the fintech industry, the need for robustness is essential. It is crucial for the regulations system to match pace with the level of innovation existing in fintech.
With a proper risk management system in place, the safety of customers and businesses can be ensured. The well-being of customers, market integrity, and financial stability depends on risk management. Fintech companies should follow some practices that could help them sustain stability and security in the market like:
Due Diligence
Conducting proper customer due diligence and verifications brings integrity and stability in the market. Adequate verifications, along with strict KYC (Know Your Customer) can help curb many problems.
Monitoring Transactions
Fintech firms should also invest in regulatory systems that help them closely monitor all transactions being conducted through them. Every purchase, every transfer, regardless of the amount should be tracked, which would help bring a level of transparency and trustworthiness in the industry.
Following Regulations
Abiding by regulations and compliance at the country and international level is crucial for fintech companies. The regulatory system is also continuously evolving alongside fintech. This requires robust changes according to the changes in fintech. For companies to keep track of and comply with all regulations, it is advisable to invest in reg-tech, which would make their systems much more efficient.

Cryptocurrencies in Fintech
The future of cryptocurrencies in the fintech industry is a question many of us would like an answer to. But before jumping to the future, let us first explore cryptocurrencies and their synthesis with fintech.

Cryptocurrencies: What are they?
Cryptocurrencies are digital currencies that are not bound by government regulations or any central authorities. These currencies use Avant Garde technology to function. Stored in blockchains, they are easily transferable and highly secure and can be used for miscellaneous purposes.
The restricted role of government authorities in regulating cryptocurrencies doesn’t make them insecure for use. These currencies function in a decentralized system and are verified using blockchain technologies.
Blockchains
In layman’s language, blockchains are digital records that are majorly used for storing information about cryptocurrencies. These are decentralized ledgers, which exist in a peer-to-peer network and are open for public use.
These ledgers contain every detail of every transaction that has ever been executed pertaining to cryptocurrencies. This public ledger is maintained in a decentralized manner, i.e., it is not governed by any centralized agencies. The level of transparency involved in blockchains ensures incredible security, as every action can be tracked and detected.
Cryptocurrencies in Fintech
The buzz surrounding cryptocurrencies is here to stay. For some, the concept of decentralized currencies is reason enough to splurge, while for others, cryptocurrencies have become an investment taboo.
Being decentralized, these currencies are immensely valued by people residing in countries where the centralized currency is volatile. A good majority of people cave into more stable options like cryptocurrencies that remain unimpeached regardless of their country’s economy.
Apart from people hailing from unstable economies, there are approximately 1 billion people who own and use smartphones but have no traditional bank accounts. Such unbanked individuals create a pool of potential cryptocurrency customers.
Benefits of Cryptocurrencies in Fintech
Efficient Money Transfers
Being set up in a decentralized platform, cryptocurrencies make money transfers easier and more efficient than traditional banks. These currencies can be used to transfer regular or even large sums of money in a matter of seconds. Traditional banking methods or even the process involved in online banking requires feeding in the information or adding beneficiaries, which take some time to get approved. Such cumbersome procedures can be completely avoided in the crypto spectrum.
More Secure Payment Systems
Any payments that are processed using cryptocurrencies are executed through blockchain technologies. This technology records every activity of every crypto coin, making the entire system very secure and safe. The element of transparency exposes all records, leaving no scope for manipulation.
Cryptocurrencies Vs. Fintech
An extremely powerful couple, cryptocurrencies and fintech are both creating a massive disruption in the way we have known and seen our world for many years. Both these elements got conceptualized a few years ago.
Although fintech has witnessed a mass adoption, especially during the pandemic, cryptocurrencies are yet to attain such a level of popularity. Having said this, the valuation of both components conveys a more remarkable story.
In 2021, a cumulative valuation of the top 100 fintech firms revealed a staggering USD 1.82 trillion. Meanwhile, the valuation of the top 100 cryptocurrencies stood at a stupendous USD 2.44 trillion. Having received much lesser acceptance by the masses, the cryptocurrency market has swelled incredibly, soaring higher than the fintech market.
Such unbelievable figures compel us to wonder about the potential cryptocurrencies possess.
The Final Word
A new age technology, cryptocurrencies are gaining momentum quite fervently. According to a report, 94% of financial experts believe that cryptocurrencies have a sparkling future in the financial industry, owing to the leverage of decentralization that they offer. Blockchain technology has not only attracted immense attention from the government but it is also being followed very closely by the banking sector.
Having a secure, open, and quick setup, blockchain technologies offer much better freedom along with safety. It is for these reasons that cryptocurrencies have so deservingly been in the limelight.

The evolution of the internet since globalization has witnessed very dynamic changes. The advent of smartphones especially has been the root of the transformation of the internet. Studies have shown that in a minute, more than 4 billion users access the internet for various reasons like shopping, searches, social media, and fintech-related activities.
The upsurge in the use of the internet and its accessories has led to an upheaval in the financial sector. People worldwide are forcibly having to stay cautious 24*7 about their data and personal information staying protected with the appropriate parties.
Cyber security is an essential unit in the fintech industry surrounding the security and safety of customer and company information and data. The number of cyber-attacks on fintech providers has grown aggressively; data and information being priceless assets in today’s world are the key incentives for hackers or malevolent parties. Anybody having access to personal and sensitive information has invaluable leverage against the vulnerable party.
Ranging from company financials to customer information, all fintech firms have access to very detailed, comprehensive, and critical data. This puts the fintech companies at great risk of getting hacked. Any lag in terms of data protection and privacy could not only result in financial damage but can also defile the company’s reputation completely.

The Benefits of Cyber Security
Regulatory Compliance
Because of the relentless growth in the fintech sector, a very robust and evolving regulatory framework has been set up at the international level. It has become mandatory for all fintech firms that meet some specific requirements created by the General Data Protection Regulation (GDPR) to comply with the regulations and guidelines outlined by GDPR. Such regulations are extremely stringent, and any lag from the company can even lead to its closure.
Financial Data Protection
Financial information is sensitive. To tackle issues concerning financial data protection, the Payment Card Industry Data Security Standard (PCI DSS) has mandated fintech companies to comply with certain policies and standards to ensure additional security. For fintech companies, such policies and regulations create directive pathways to follow, making it slightly easier for them to provide data protection and security. However, such stringent and mandatory practices also demand more resources and investments from the company, as cyber security becomes an unavoidable and independent department that goes along the way.
Company Reputation
The majority of the data that any fintech company acquires from its customers is very sensitive. Any oversight in this respect can jeopardize the company’s future. Hackers and evil parties are always on the lookout for companies that either have failed to follow the regulatory guidelines adequately or have mistakenly left any lags. Such gaps in the company can damage its reputation catastrophically and eventually put its future at risk.
Cyber Security Issues in Fintech
Since the onset of fintech, the partnership between traditional financial institutions and fintech services providers has multiplied rapidly. Such partnerships obligate easy transfer of data and information between the two parties. If either of the party fails to monitor and regulate their procedures, it could lead to multiple complications.
According to one study, less than 50% of fintech firms invest in security and data protection. More than 90% of fintech companies at one point had failed in identifying the root causes of data breaches in their systems. Approximately two-thirds of the fintech had stored data in an unencrypted format, compromising the level of security even further. One-fifths of the passwords chosen by customers to login into their fintech portals could be hacked and revealed because of a lack of proper authorization and regulations.
Such studies have continuously highlighted the foul side of the sudden upsurge of fintech. With personal and financial data floating on the internet, it is a matter of immense concern for all customers.
During the pandemic, the fintech industry got propelled to a broader reach, where people had to adopt alternatives to customary banking methods. Because of so many people becoming aware of fintech and adapting to the changing environment of the financial world, the strictness in the regulations and standards has escalated, bringing some decorum to the dynamic interplay of fintech.
Main Underlying Reasons for Cyber Threats
The main reasons identified after studying several individual fintech cases and scenarios are:
- Unsafe Market Practices – Before the introduction of fintech, people all over the world had become accustomed to basing their transactional and financial affairs on trust and integrity and payment was mostly dealt in cash. With the emergence of smartphones combined with the increase in the number of middle parties involved in one transaction, the number of opportunities for hackers has grown. People leaving their accounts logged in, sharing their one-time passwords on phone, or even sharing their credit/debit card information over the phone have spiked the percentages of hacking.
- Rapid Automation – With more people valuing fintech services and the convenience that comes along with them, the need for automating simple processes has gone up. Streamlined operations put the entire system at risk if the automation doesn’t take cyber threats into account. Keeping up with fintech regulations, while staying dynamic in their services is a challenge many fintech firms face.
- Competition – The rapid increase in demand for fintech services has resulted in intensified competition levels. Fintech startups all over the world are trying to bring down their cost and increase their services. This catapults the system into the unstable ground. To lessen costs, firms try and cut down on their investments, including security. Apart from this, innovation is cruising globally empowering new startups to come up with innovative ideas and technology, which is immediately floated in the market, without any exhaustive testing of its data protection and security gaps.
Such monumental issues need strictness and obligatory regulations and policies to bring back the lost balance. The fintech environment is ever-changing, and with such dynamic evolution, it becomes highly imperative to put some restraints and bind uncontrolled factors from causing serious damage.
Cyber threats have been on a rise in the past few years, but cyber security has now become an essential practice that has successfully lessened the number of opportunities hackers and malevolent agents get to exploit the system. With such stringent measures becoming mandatory for new and old fintech firms, the fintech market is finally settling into good shape.

Stimulated by people’s quick adaptation to smartphones and computers, the wave of fintech has been propelled further by the pandemic. This industry came out as the true winner during the pandemic, by escalating its influence and impact on the everyday lives of billions of people worldwide.

Top Global Fintech Hubs
Since the onset, the United States of America has been the global leader in the fintech industry. The number of fintech unicorns, other companies, and startups has risen astronomically, not only in the US but all across the world. The fintech sector has disrupted the usual ongoing in all other sectors by changing the face of financial services.
The Silicon Valley in the San Francisco Bay Area, US, has been declared the bed of technological developments in different industries. With more than 200 fintech startups, the place tops the list of world fintech hubs.
The city of London in the United Kingdom is the second world leader in fintech hubs. Dominated by the financial technology market, the city now has close to 200 startups, revolutionizing people’s perception of fintech.
New York is the third world leader vis-a-vis global fintech hubs. The city has always been accepted as the financial capital of the world, because of its dominance in the financial market and the advent of fintech in New York only seems like a natural course of its mark.
The fourth city-state to reach the top five list of fintech hubs is Singapore. With more than 70 startups providing financial and trade services globally, Singapore has reeled in the attention of the world.
The fifth city to make the cut is Los Angeles, in the US. With lower employment costs compared to New York and the Silicon Valley, and talent pouring in, this city has earned its supremacy in the fintech industry. It has more than 60 startups rendering it pivotal in the fintech industry.
Three-fourths of the fintech activities worldwide are mainly dispersed across US and Europe. Together these places account for more than 1600 fintech firms, playing the lead role in the industry. Fintech activities are not constricted to these dominants, as they are growing at an expeditious rate worldwide, with countries like Germany, Japan, and India reporting a stupendous growth chart.
Biggest Fintech Players
USA
Visa and MasterCard, also known as the originators of fintech, are still global leaders. With a market valuation of more than $400 billion, Visa stands to be the world leader in fintech. It is closely followed by MasterCard, which has been valued at $350 billion. Even though these companies hold mighty valuations, their service categories don’t necessarily make up mainstream fintech.
Fintech firms like Intuit, PayPal, Square, and Chime have been the real fintech players in the United States.
With a valuation of over $100 billion, Intuit is the largest fintech services provider in North America. PayPal is a cardinal fintech player, which has become the voice of fintech for companies and individuals all over the world by providing e-payment and e-transfer platforms and services. It has been estimated at a little less than $100 billion.
UK
Being a global fintech hub, the UK has developed a fintech army disrupting traditional banking methods. Companies like Checkout.com and Revolut, with individual valuations of approximately $40 billion, are taking the country to the center stage of fintech.
China
The largest conglomerate of fintech resides in China – Ant Financial. The company majorly falls in the open banking category, with a number of subdivisions like AliPay, which are leading the world in terms of innovation and turnover. With a staggering estimate of more than $300 billion, the company is the largest fintech player in the world.
Others
The key players in the rest of the world are housed in tiny pockets like Stripe in Ireland, Gojek in Indonesia, Klarna in Sweden, Nubank in Brazil, Grab in Singapore, and at least a hundred more.
The instant revolution that is being experienced by the world in the fintech industry is incomparable. With the sudden surge in adoption and demand for fintech services and products, it has become an indispensable industry that is changing the way the financial sector functions.
The true potential of technology has just started grabbing our attention and one cannot possibly fathom how far we can go from here.


Where We Made the Difference
The solution was devised as not only a way to embrace digital but also to create a unique model to offer cashback at offline merchants. This enabled the offline retailers to match their online shopping counterparts in creating customer loyalty by integrating proven contactless solutions.

The Agrani Remit app is an excellent example of how digital innovation helped the Bangladeshis working in Singapore to digitally and conveniently remit money, back to their family members safely…

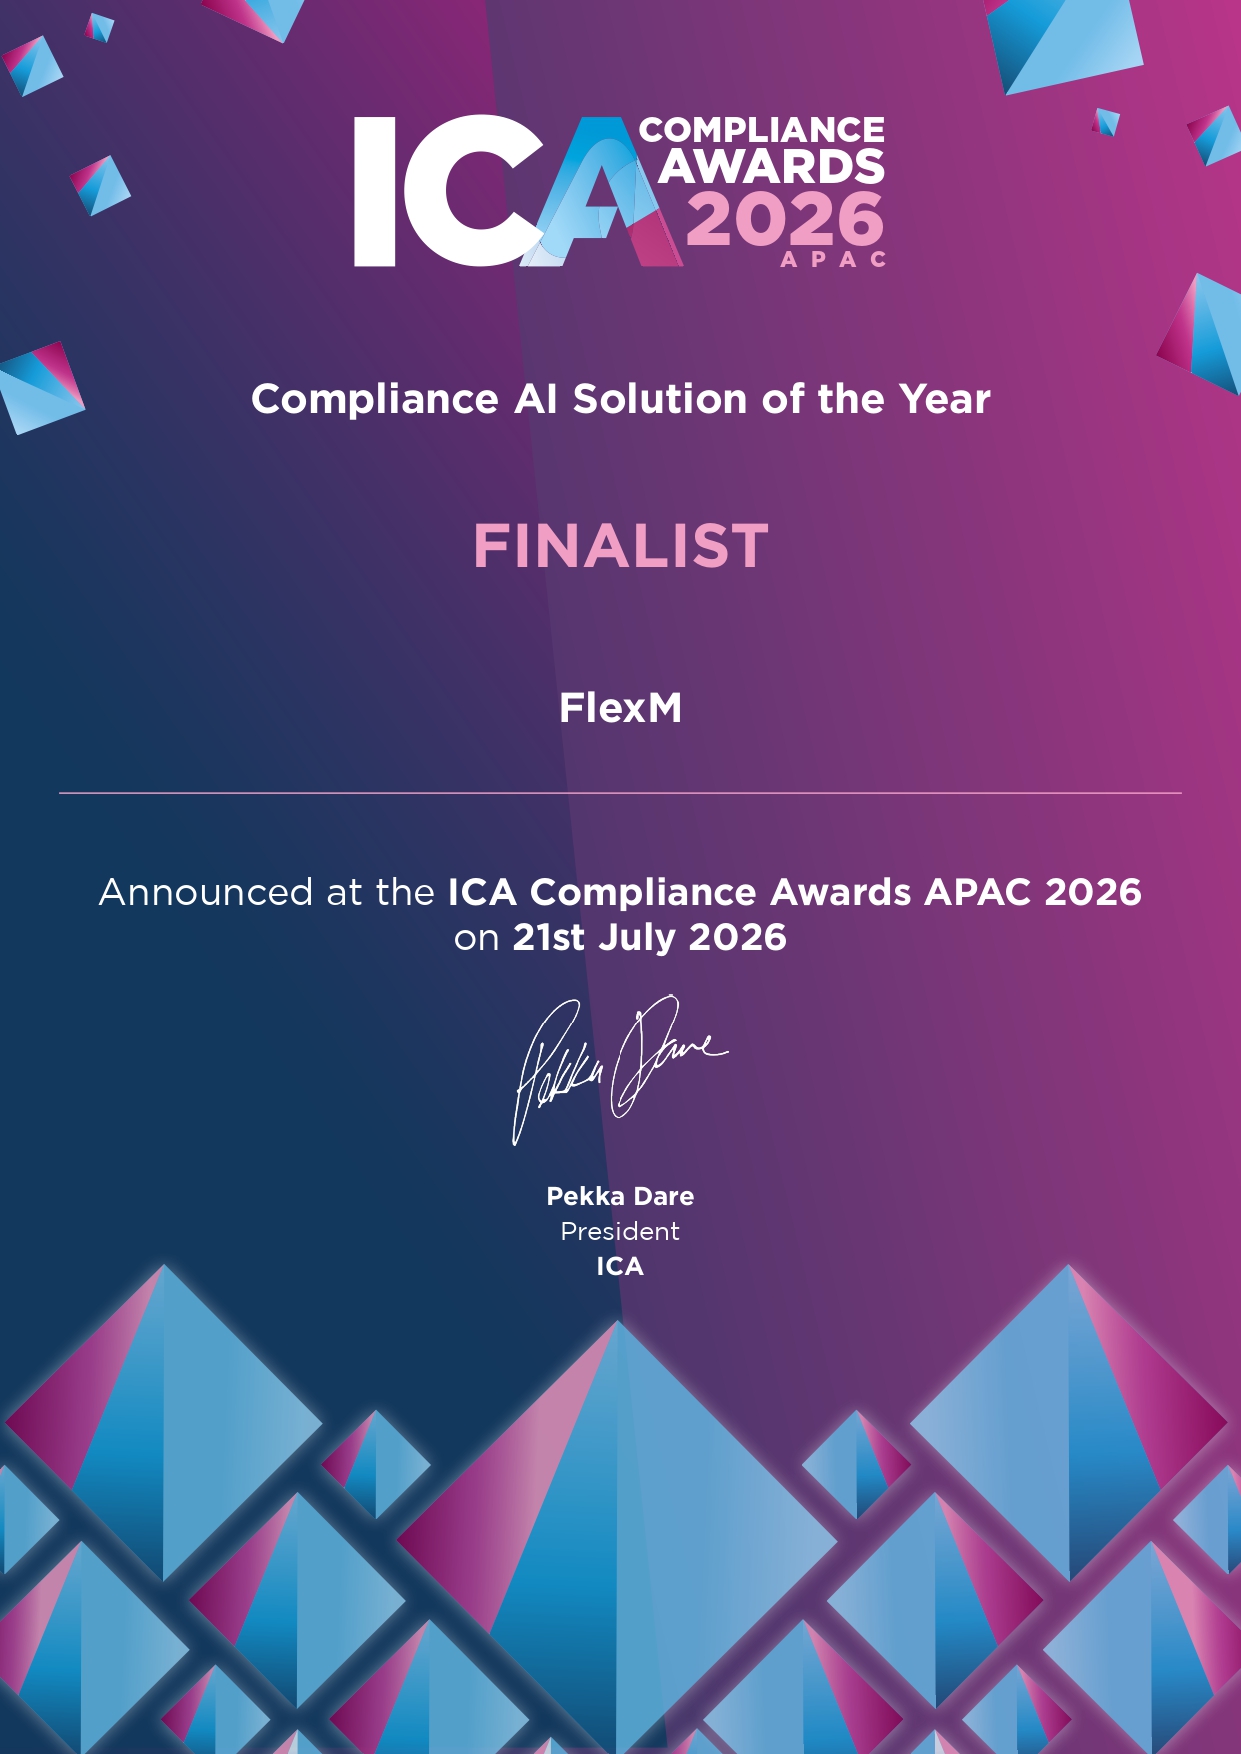
FlexM, one of our collaborative partners, played a crucial role in conceptualizing the solution (FlexM's Compliance Solution). Their continued support throughout this transition has been invaluable. We are grateful for FlexM's significant contribution to the solution and their unwavering support as we navigate this transition.

FlexM offers invaluable (RegTech) services for monitoring our card transactions and reporting to the RBI. Their expertise and commitment to excellence have significantly enhanced our compliance and risk management processes.